
Anthropic filed its registration statement at 9:00 am Eastern on October 26, an hour after SpaceX filed a $40 billion GPU lease commitment. On October 23 this shelf wrote down five questions for the filing, drawn from The Other Side of the Headline, each with the possible answers and what each would mean, so the reading could not be fitted to the result. Revenue was the first question. This is the first read of that answer, with the others in brief. The full read follows before the roadshow. (1)
The revenue is gross
The question was whether sales through the cloud marketplaces of Amazon, Google and Microsoft count as Anthropic's revenue at what the customer pays, or at what the cloud partner passes on. ASC 606 decides it by asking who controls the service before it reaches the customer. (2)
Anthropic answers in its accounting policies. In these arrangements, "the Company is the principal and recognizes revenue on a gross basis because the Company has a direct contractual relationship with customers, is primarily responsible for providing the intelligence service to customers, and establishes pricing." The cloud partners, the policy continues, "do not obtain control of the Company's intelligence service at any point prior to transfer to the customer." (3)
So revenue is booked at what the customer pays, less taxes collected for others and estimated concessions, credits and refunds, and the partners' fees are an expense. The channel is large. Sales through the cloud marketplaces were about 32 percent of revenue in 2024, 47 percent in 2025 and 48 percent in the first half of 2026, and 58 percent of receivables at June 30. The S-1 describes the cloud partners as "distribution and billing channels" that "bill end customers, collect payments on our behalf, and remit such amounts to us, net of applicable platform and other fees." (4)
The partners' fees sit in sales, marketing and partnerships, which rose from $120 million in the first half of 2025 to $3,168 million in the first half of 2026, "primarily driven by a $2.7 billion increase in fees paid to channel partners." Compute and infrastructure separately carries "infrastructure costs associated with serving customer workloads through partner channels." (5)
The S-1 adds an estimate that bears on revenue itself. Revenue from customers later found to be using its models in violation of its usage policy or commercial terms "represented approximately 5% to 7% of our revenue for the nine months ended September 30, 2026." The company recognizes that revenue as the services are provided, before restricting access. It calls the dynamic common in the industry and expects the share to decline, citing enforcement it stepped up in August and September 2026, and it describes the timing and size of any effect on revenue as uncertain. (6)
One part of the question stays open. Amazon and Google are each investor, compute supplier and distribution channel to Anthropic. If either is also a customer, ASC 606 asks what payments to it buy: a payment for a distinct good at fair value is a purchase, and the rest comes off revenue. The accounting policies address control. A search of the filing's main document for the standard's phrase, consideration payable to a customer, and for its common variants, returns no result. The full read takes it up through the note purchase agreements in Note 4. (7)
The quarters, and the one in ratio form
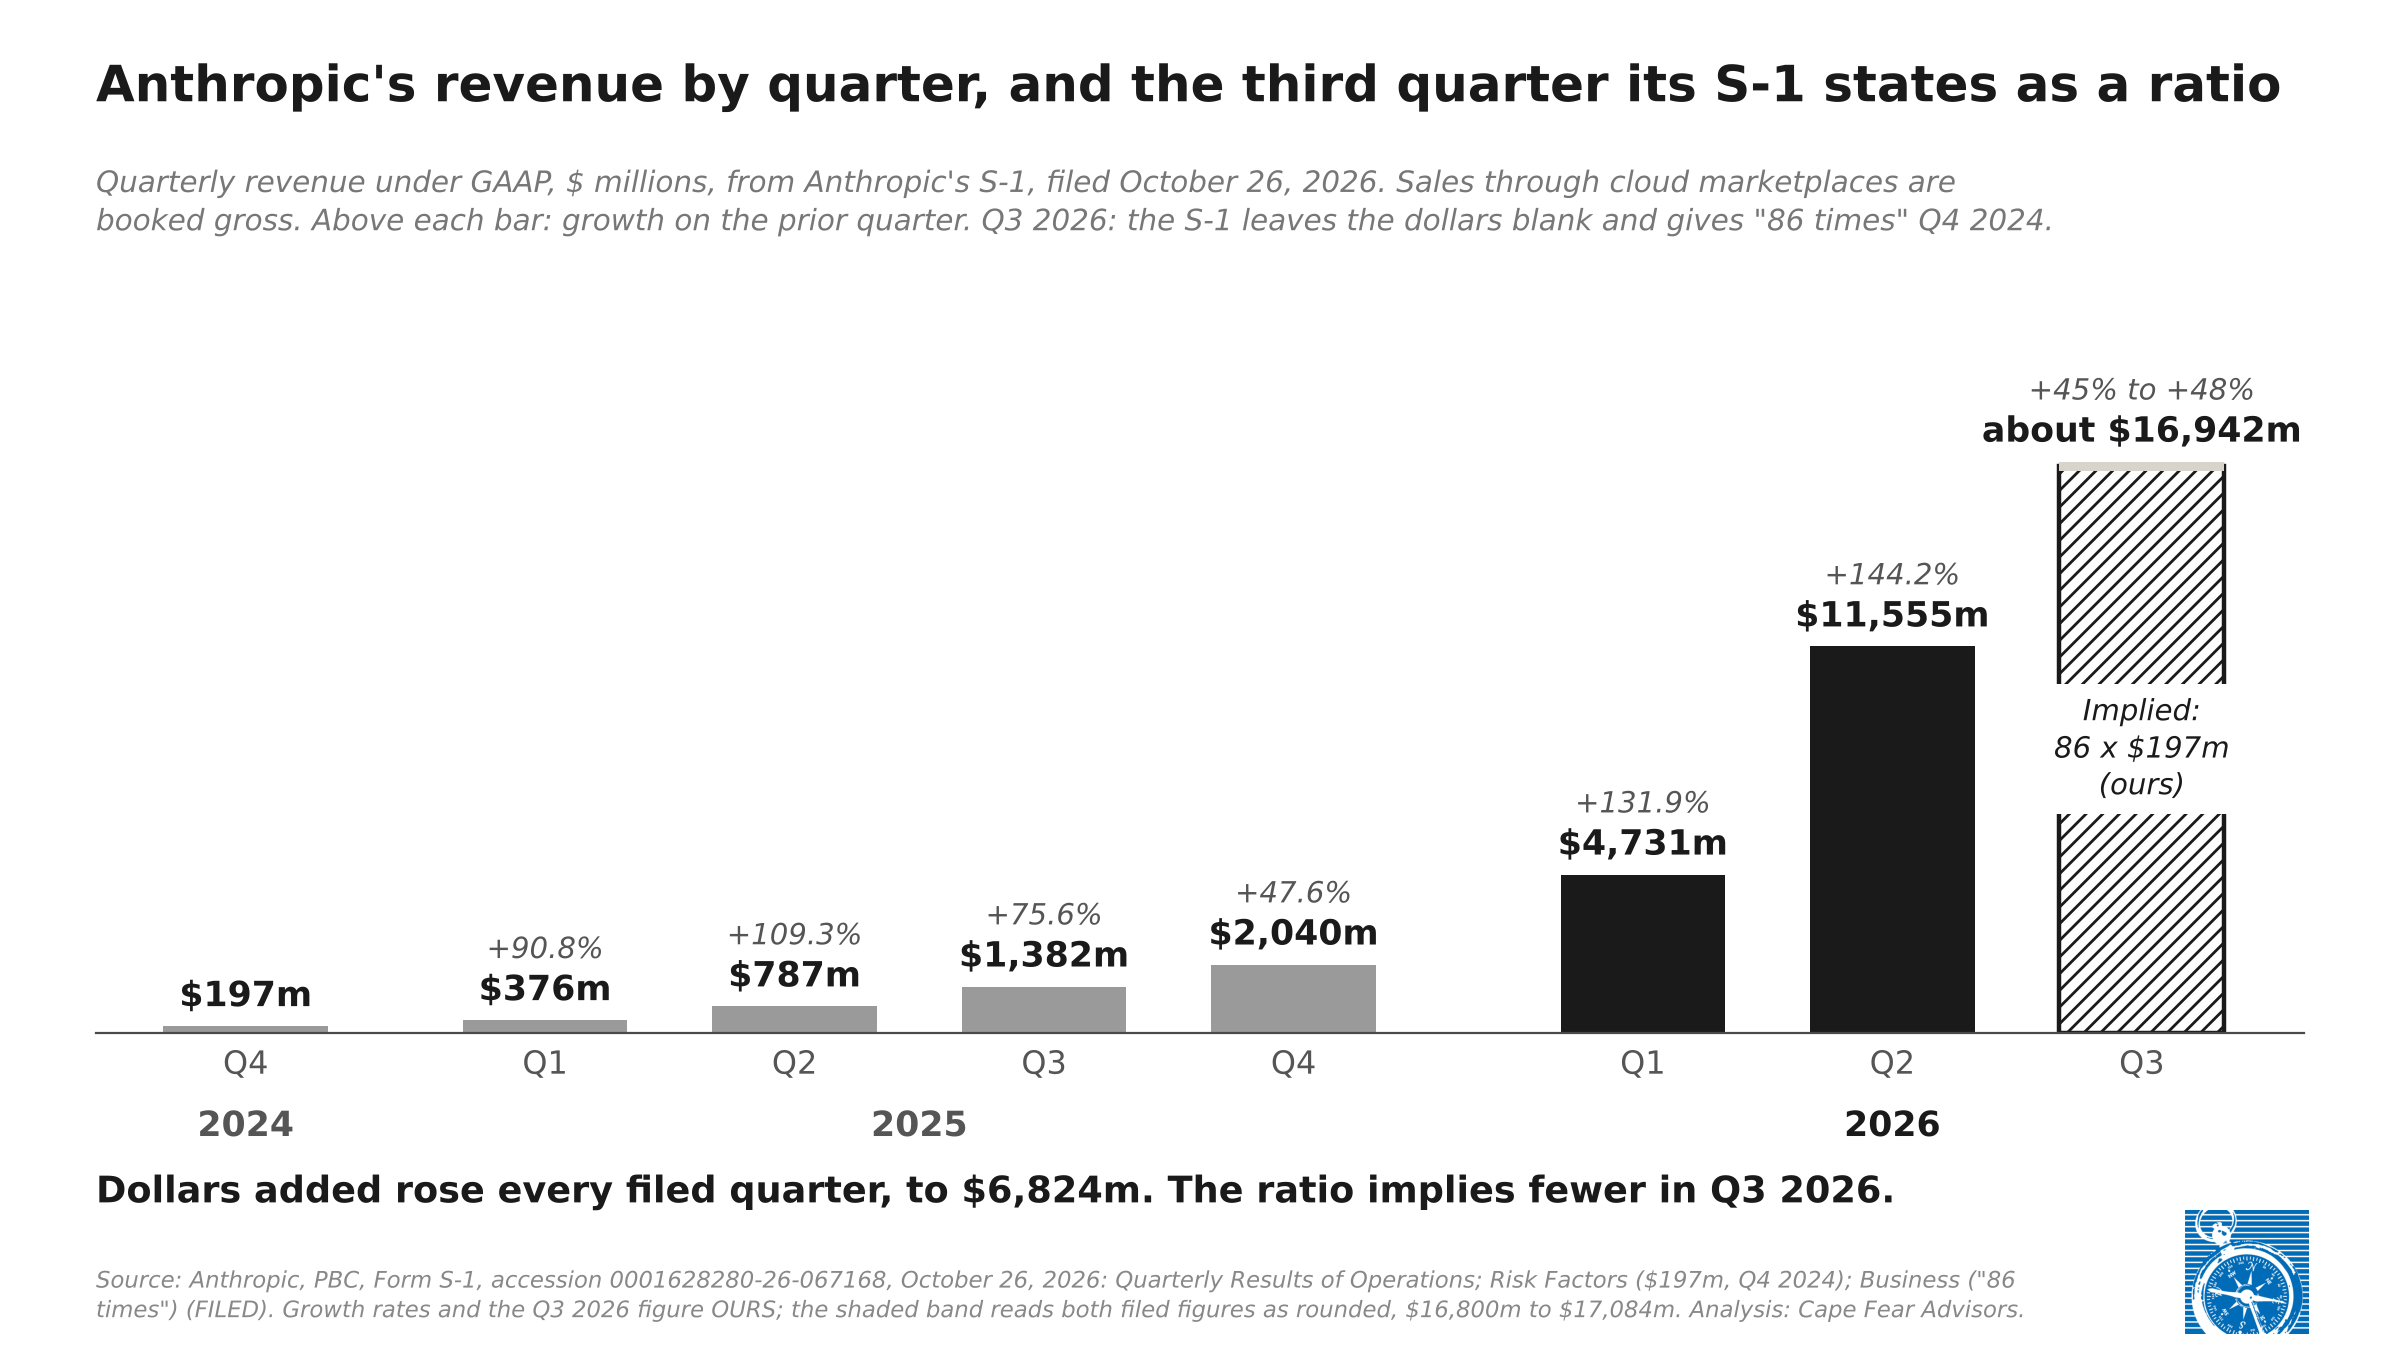
The S-1 files six quarters in its quarterly table and a seventh, the last quarter of 2024, in its risk factors, at $197 million. (8)
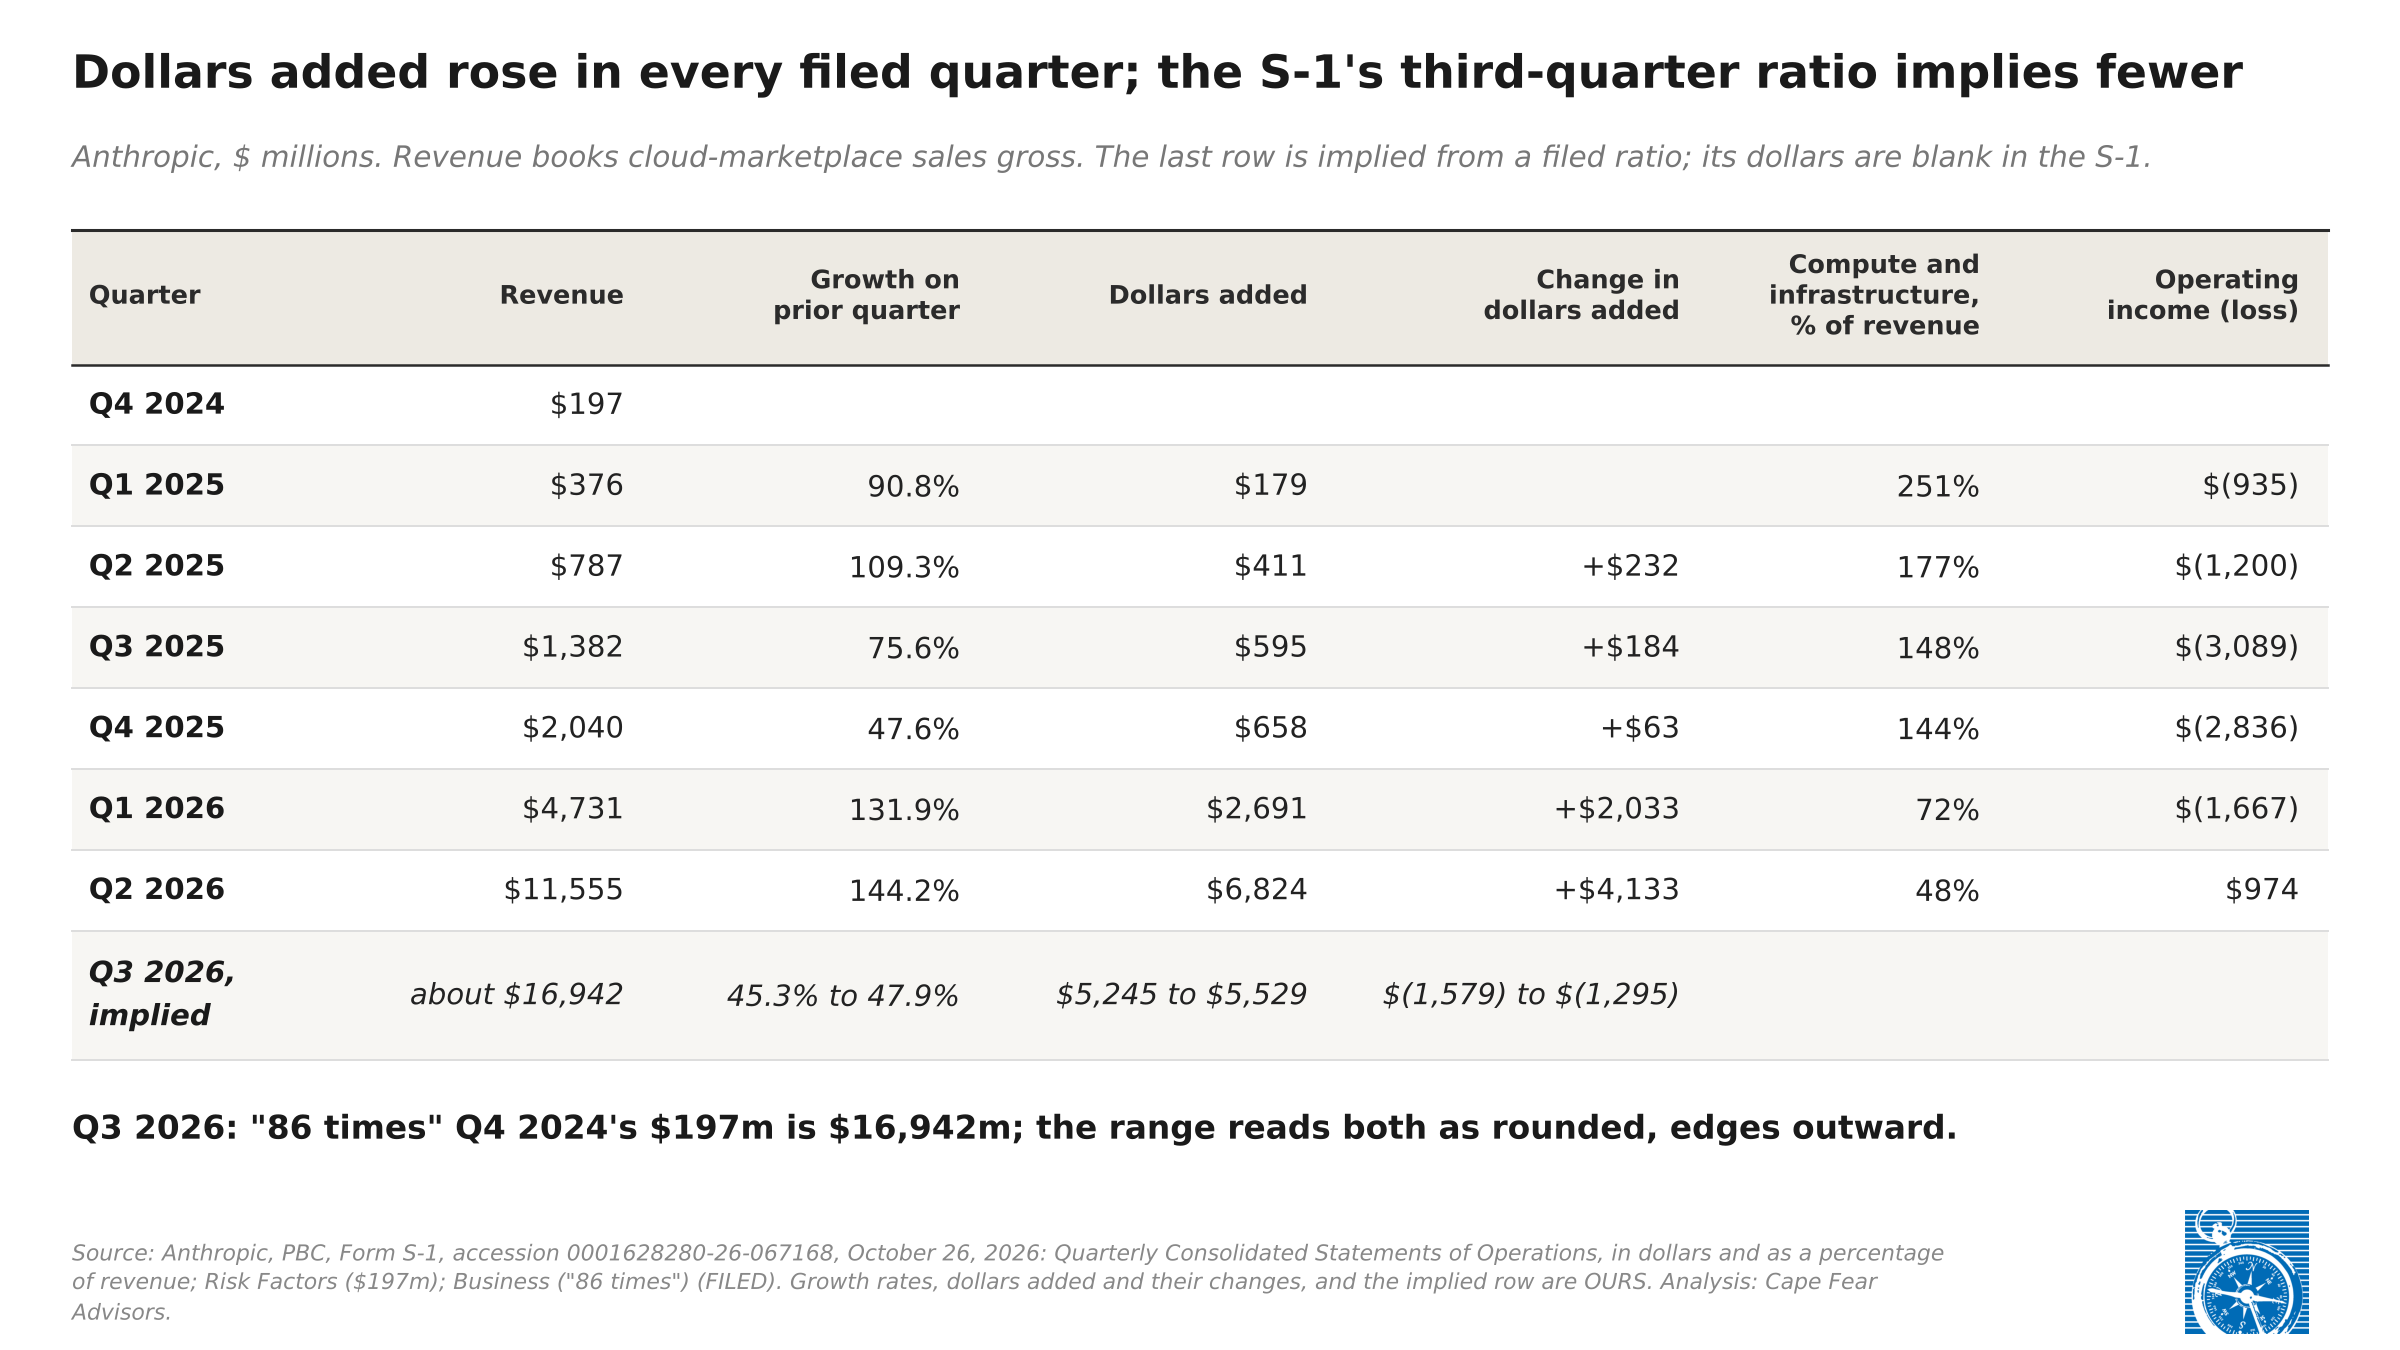
The dollars added grew in every filed quarter, from $179 million in the first quarter of 2025 to $6,824 million in the second quarter of 2026. The growth rate turned more than once along the way: it rose into the second quarter of 2025, fell in the third and fourth, and rose in both quarters of 2026, to 131.9 and 144.2 percent. The company attributes the increases to "successive model and product releases that drove higher usage, expansion, and broader adoption." (9)
Costs moved the other way as a share. Compute and infrastructure fell from 251 percent of revenue in the first quarter of 2025 to 48 percent in the second quarter of 2026, which the company explains as compute bought "12 to 18 months in advance of availability" and fixed in the near term. The second quarter of 2026 is the first of the six with an operating profit, $974 million. (10)
The S-1's statements run to June 30, and the third quarter's dollars are blank where the risk factors give the growth from $197 million. The Business section states the same quarter as a multiple: revenue for the three months ended September 30, 2026 "was 86 times our revenue for the three months ended December 31, 2024." On the filed $197 million, that is about $16.9 billion, and with both figures read as rounded, $16.8 billion to $17.1 billion. That is growth of about 45 to 48 percent on the second quarter, and about $5.2 billion to $5.6 billion added, the first quarter in the series to add fewer dollars than the one before. The Financial Times reported $16.8 billion. The amendment that fills the blank settles it. (11)
The run-rate is defined, and its value is blank
Run-Rate Revenue is consumption fees for the trailing 28 days times 13, plus monthly subscription fees times 12. The S-1 carries one value, and it reads "our Run-Rate Revenue was $ as of October 31, 2026," a measurement date five days after the filing. The S-1's text carries no history of the metric. (12)
The history the S-1 does carry is in customers. Customers with $100,000 or more of trailing twelve-month revenue numbered about 400 at March 31, 2025, more than 950 at September 30, 2025, more than 6,000 at June 30, 2026 and more than 11,900 at September 30, 2026. Net revenue retention was about 900 percent at September 30. (13)
Commitments, from the buyer's side
The S-1 names its largest compute arrangements one by one. At least $44.9 billion with Microsoft, at least about $114.5 billion with Google and at least $110.0 billion with Amazon are non-cancelable except in the event of the supplier's uncured material breach, with true-ups at Google and Amazon and a per-tranche exception for undelivered capacity at Microsoft. Broadcom's five-year equipment leases carry about $161.2 billion of rent, excluding interest. Nscale's agreements run up to about $44.6 billion, matching Nscale's own S-1 as read in What the Price Believes: Nscale, and Lambda's about $41.3 billion, of which, for the $34.9 billion August agreement, "either party may terminate if Lambda does not timely secure the facility lease." (14)
The seven named lines come to $637.0 billion, a scale that adds minimums, ceilings and rent; the S-1's own total is blank. One of the seven, SpaceXAI, may be canceled by either party on 90 days' notice after its initial periods. (15)
SpaceX, the same morning
At 8:00 am, SpaceX filed an 8-K on a binding commitment letter, signed October 24, to enter a master finance lease with an entity managed by Apollo. The Apollo entity buys the GPU pods and leases them to SpaceX in tranches of approximately five to five and one-quarter years, with rent each quarter in advance of one-twentieth of the financed cost plus a fixed rate set at pricing. Principal is expected to total about $40 billion. The lease is subject to closing conditions and expected to close before year end, and the schedules are expected to commence in the first half of 2027, as the GPUs are delivered. (16)
At 9:00 am, Anthropic filed the terms of its contracts with SpaceXAI. It agreed to spend up to $120.5 billion over terms extending into 2029, about $3.1 billion a month once all capacity is delivered, expected in December. "Following initial non-cancelable periods ending in January 2027 and March 2027 under the respective agreements, each agreement may be cancelled by either party upon 90 days' advance written notice." SpaceXAI is 18.9 percent of the seven named lines. (17)
SpaceX's lease schedules are expected to commence in the first half of 2027 and run about five years. Anthropic's contracts with SpaceXAI become cancelable by either party on 90 days' notice from January and March 2027. Both dates are filed, by different companies, an hour apart. The filings leave unstated which GPUs serve which customer. (18)
SpaceX's own 10-Q describes its compute contracts in similar terms, "typically three years and terminable by either party upon 90 days' notice," and its largest customer in the third quarter, unnamed in that filing, was 34.5 percent of revenue. The October 25 piece read the same term structure across the builders' filings: five years of rent, ninety days of notice. (19)
The loss sits below the operating line
The first half of 2026 lost $80,748 million, and $693 million of it was operating loss. Below the operating line sit a $72,388 million charge for the change in fair value of convertible notes and related instruments, which the company attributes primarily to the rise in its valuation, and a $9,405 million charge on the note purchase agreements, offset in part by $1,111 million of interest income and a $724 million gain on warrant rights. Cash and short-term investments were $131.7 billion at June 30. (20)
What we are watching
The amendment that carries the price range and fills the third quarter and the October 31 run-rate. Note 4 and the material-contract exhibits, for the two-way flows with Amazon and Google. The definitive Apollo lease. The full read scores all 198 rows of the answer key written before the filing.
Free to read, no paywall. Readers who find the work useful can support it at the foot of the page; payment offsets the time and buys no access. Corrections run in daylight, dated, in a comment or in the following piece, and a reader who finds one is doing us a favor.
Standing Disclosure
Anthropic is the developer of Claude, which is used in preparing this research, and Anthropic is the filer read here. That nearness cannot be fully checked away, which is why no claim in this piece rests on trust in the tool: every figure carries a public source, and the record grades the rest. Others named in this piece have ties to Anthropic: Amazon, Google and Microsoft are compute suppliers and distribution channels, and Amazon and Google are investors; Broadcom leases equipment to Anthropic; SpaceX, Nscale and Lambda supply compute. Companies not named here, among them the chip suppliers behind the capacity, may hold positions or supply relationships that bear on the filer, and that possibility is part of why every piece is re-checked for bias, ground facts, and filings rather than read against a fixed list. Figures are quoted from the filers without characterization, and the same standard of reading is applied to every filer named.
Notes
[1] FILED. Anthropic, PBC (CIK 2130357), Form S-1, accession 0001628280-26-067168, file no. 333-299633, accepted 9:00:11 am ET October 26, 2026. The price range, share counts and contractual-obligations table are blank in this filing. EDGAR probe, 14:46 UTC October 26: the S-1 is the latest filing on the registrant's docket, with no amendment. The five questions and their possible answers: Cape Fear Advisors read kit, October 23, 2026, built on "Adding It Up: The Other Side of the Headline," October 10, 2026.
[2] ASC 606-10-55-36 to 55-40, principal versus agent considerations.
[3] FILED. S-1, Notes to Consolidated Financial Statements, Note 1, Description of Business and Summary of Significant Accounting Policies, Revenue Recognition (pages F-21 to F-22).
[4] FILED. S-1, Note 1, Revenue Recognition ("Revenue excludes amounts collected on behalf of third parties, such as sales and indirect taxes, as well as estimated concessions, credits, and refunds"); Risk Factors, for the channel shares, which the S-1 gives as approximately 11, 32, 47 and 48 percent for 2023 to 2025 and the six months ended June 30, 2026, and the shares of net accounts receivable (42, 60 and 58 percent at December 31, 2024 and 2025 and June 30, 2026), and for "distribution and billing channels."
[5] FILED. S-1, MD&A, comparison of the six months ended June 30, 2025 and 2026; Note 1, Compute and Infrastructure. The $2.7 billion is an increase, and the level of channel fees is unstated.
[6] FILED. S-1, MD&A, Components of Results of Operations, Revenue: "we estimate that revenue from such customers represented approximately 5% to 7% of our revenue for the nine months ended September 30, 2026. This estimate requires judgment and may change as our detection methodologies evolve and we identify previously undetected usage." The same passage carries "We believe this dynamic is common in our industry" and the expected decline. The Risk Factors carry the parallel disclosure for Run-Rate Revenue.
[7] OURS, on FILED. ASC 606-10-32-25 to 32-27. Text searches of the S-1 main document for "consideration payable," "payable to a customer," "payments to customers," "consideration paid to," "reduction of revenue," "contra revenue," "distinct good" and "606-10-32," run between 13:30 and 14:27 UTC October 26, 2026, returned zero results; exhibits were not searched. Note 4 describes the note purchase agreements.
[8] FILED. S-1, MD&A, Quarterly Results of Operations (six quarters, March 31, 2025 to June 30, 2026); Risk Factors, "our revenue increased from $197 million for the three months ended December 31, 2024 to $ for the three months ended September 30, 2026."
[9] OURS, on FILED. Growth: 376 over 197 is 1.9086, or 90.8 percent; 787 over 376 is 2.093, or 109.3 percent; then 75.6, 47.6, 131.9 and 144.2 percent. Dollars added: 179, 411, 595, 658, 2,691 and 6,824. Every rate is rounded down. The six quarters foot to the filed half years: 376 plus 787 is 1,163, and 4,731 plus 11,555 is 16,286. The company's attribution: MD&A, Quarterly Trends.
[10] FILED. S-1, Quarterly Consolidated Statements of Operations, as a Percentage of Revenue; Quarterly Trends, Compute and Infrastructure. Operating income for the three months ended June 30, 2026, $974 million.
[11] FILED and OURS. FILED: S-1, Business, "our revenue for the three months ended September 30, 2026 was 86 times our revenue for the three months ended December 31, 2024"; Risk Factors, $197 million. OURS: 86 times 197 is 16,942. Read as rounded, 85.5 times 196.5 is 16,800.75 and 86.5 times 197.5 is 17,083.75. Against 11,555, growth is 45.398 to 47.847 percent and the dollars added are 5,245.75 to 5,528.75, against 6,824 in the second quarter. Every edge of every printed range is rounded outward. REPORTED: Financial Times, third-quarter revenue of $16.8 billion, set beside the filed range and used in no calculation.
[12] FILED. S-1, Prospectus Summary glossary, "Run-Rate Revenue"; Business, where the value and the date of October 31, 2026 appear with the amount blank. The text search returned the definition, risk-factor and footnote uses and this one blank; the charts read carry no run-rate value, and the S-1's other images were not read.
[13] FILED. S-1, MD&A, Quarterly Trends (about 400 at March 31, 2025; more than 6,000 at June 30, 2026); Business (more than 950 at September 30, 2025; more than 11,900 at September 30, 2026). Both sections count customers with $100,000 or more of revenue on a trailing twelve-month basis. Net Revenue Retention of about 900 percent at September 30, 2026: Prospectus Summary, defined in the glossary.
[14] FILED. S-1, MD&A, Contractual Obligations, Infrastructure Service Arrangements and Infrastructure Equipment Leases. Nscale: Nscale Ltd Form S-1, accession 0001193125-26-395475; Nscale must use best efforts to obtain qualifying financing within a specified period, and fees accrue only as capacity is delivered and accepted. Google's further TPU procurement, estimated at $125.0 billion to $150.0 billion for 2028 to 2031, and AMD's, expected to exceed $20.0 billion, sit outside the contractual-obligations table and outside the seven lines in note (15).
[15] OURS, on FILED. 44.9 plus 114.5 plus 110.0 plus 120.5 plus 44.6 plus 41.3 plus 161.2 is 637.0. The lines mix minimums ("at least"), ceilings ("up to") and rent excluding interest; the sum is a scale, and the S-1's own total is blank.
[16] FILED. Space Exploration Technologies Corp. Form 8-K, Item 8.01, accession 0001104659-26-118614, accepted 8:00:18 am ET October 26, 2026.
[17] FILED. S-1, MD&A, Infrastructure Service Arrangements, the SpaceXAI Arrangements. OURS: 120.5 over 637.0 is 18.9 percent.
[18] FILED. The 8-K, note (16), and the S-1, note (17). The two acceptances are 60.9 minutes apart. Both filings leave the allocation of equipment to customers unstated.
[19] FILED. SpaceX Q3 Form 10-Q, accession 0001628280-26-066880: MD&A revenue policy for cloud services, and Customer B at 34.5 percent of third-quarter revenue. The 10-Q leaves Customer B unnamed. OURS, "Anthropic, First Read: The Revenue Is Gross, and the Third Quarter Is a Ratio," October 25, 2026.
[20] FILED. S-1, Consolidated Statements of Operations and its footnote on the change in fair value ("primarily driven by an increase in the fair value of our outstanding convertible promissory notes resulting from an increase in our enterprise valuation"); Note 8, Supplemental Financial Information, Other Income (Expense), Net, which also carries $39 million for a holdback liability and $37 million of other items. The lines tie: 693 plus 72,388 plus 9,405 plus 39 plus 37, less 1,111 and 724, plus a $21 million tax provision, is 80,748. Market Risk: $112.4 billion of cash and equivalents and $19.3 billion of short-term investments at June 30, 2026.
Analysis: Cape Fear Advisors.
This piece also appears on Substack. Cape Fear Advisors is an independent advisory firm based in Portsmouth, NH.
Contact Cape Fear Advisors