
Anthropic filed its amended registration statement on Monday. It answers several questions our three earlier readings left open, and it puts numbers on two things the first filing described only in words: the short-term compute Anthropic buys when demand outruns its long-term capacity, and the capacity that waits on another company's financing, facilities or approvals. Side by side, the two give the compute calendar a shape. The line either side can end opens before the lines meant to replace it arrive. Those lines wait on financing raised against contracts. The seller of the first line borrows against itself.
What the amendment answered
The third quarter is now in dollars. Revenue was $16,956 million. (1) Our first read stated the quarter as the filing then did, as a ratio, "86 times" the fourth quarter of 2024, and derived a band of $16,800 million to $17,084 million around a point of $16,942 million. The filed figure sits inside the band, $14 million above the point. (2)
"The Growth Gap" found that the third quarter added fewer dollars than the second, the first quarter on the record to do so. On the filed figures it added $5,401 million against $6,824 million. (3) Rebuilt on the filed quarter, the two paths that piece set for the next four quarters move by less than a percent: $81.7 billion on the slowdown path, against $81.6 billion printed, and $193.6 billion at the third quarter's pace, against $193.0 billion. (4)
Two figures are still blank: the price range, and Run-Rate Revenue as of October 31. The estimate of revenue from customers that violated the usage policy is unchanged, 5% to 7% of nine-month revenue, now nine months through September, with no quarterly split. (5) The sensitivity we added to "The Growth Gap" on October 30 therefore stays open, and it carries here under its own heading below.
The bridge, sized
The first filing said short-term compute "typically carries a higher cost per unit." The amendment puts a number on it. In the third quarter, "our underlying compute efficiency improvements were partially offset by the delivery of additional compute, including $5.0 billion of compute under short-term commitments, which currently costs significantly more than comparable compute procured under our multi-year commitments. This reduced revenue per dollar of compute compared to the preceding quarter." (6)
The quarter shows it. Compute and infrastructure expense rose 77.4% to $9,863 million while revenue rose 46.7%, so each dollar of revenue carried 58 cents of compute, against 48 cents in the second quarter. The filing attributes the third quarter's $567 million operating loss "primarily" to the $5.0 billion of short-term compute and to $2.0 billion of non-cash donation-matching charges, and the fall in Adjusted Operating Margin from 19% to 15% "primarily" to the short-term compute. (7)
Both filings carry a sentence that now has a figure to attach to: "The flexibility from Anthropic Direct allows us to backfill the short-term compute we procure during periods of high demand with more cost-effective, long-term compute as our dedicated infrastructure comes online." (8) Anthropic Direct is leased chips in dedicated facilities, with data center capacity secured early and accelerator commitments deferred "until our specific compute needs are more certain." The amendment leaves that description as it was and sizes what is to be backfilled: $5.0 billion in a quarter.
Anthropic does not name the provider of that compute. SpaceX does not name the customer behind its Customer B, which was 34.5% of its third-quarter revenue, $5,028 million. Bloomberg reported on October 29 that Customer B is Anthropic. (9) The buyer's short-term compute and the seller's largest customer each came to about $5.0 billion in the third quarter. Neither filing joins them, and we draw no identification beyond the report.
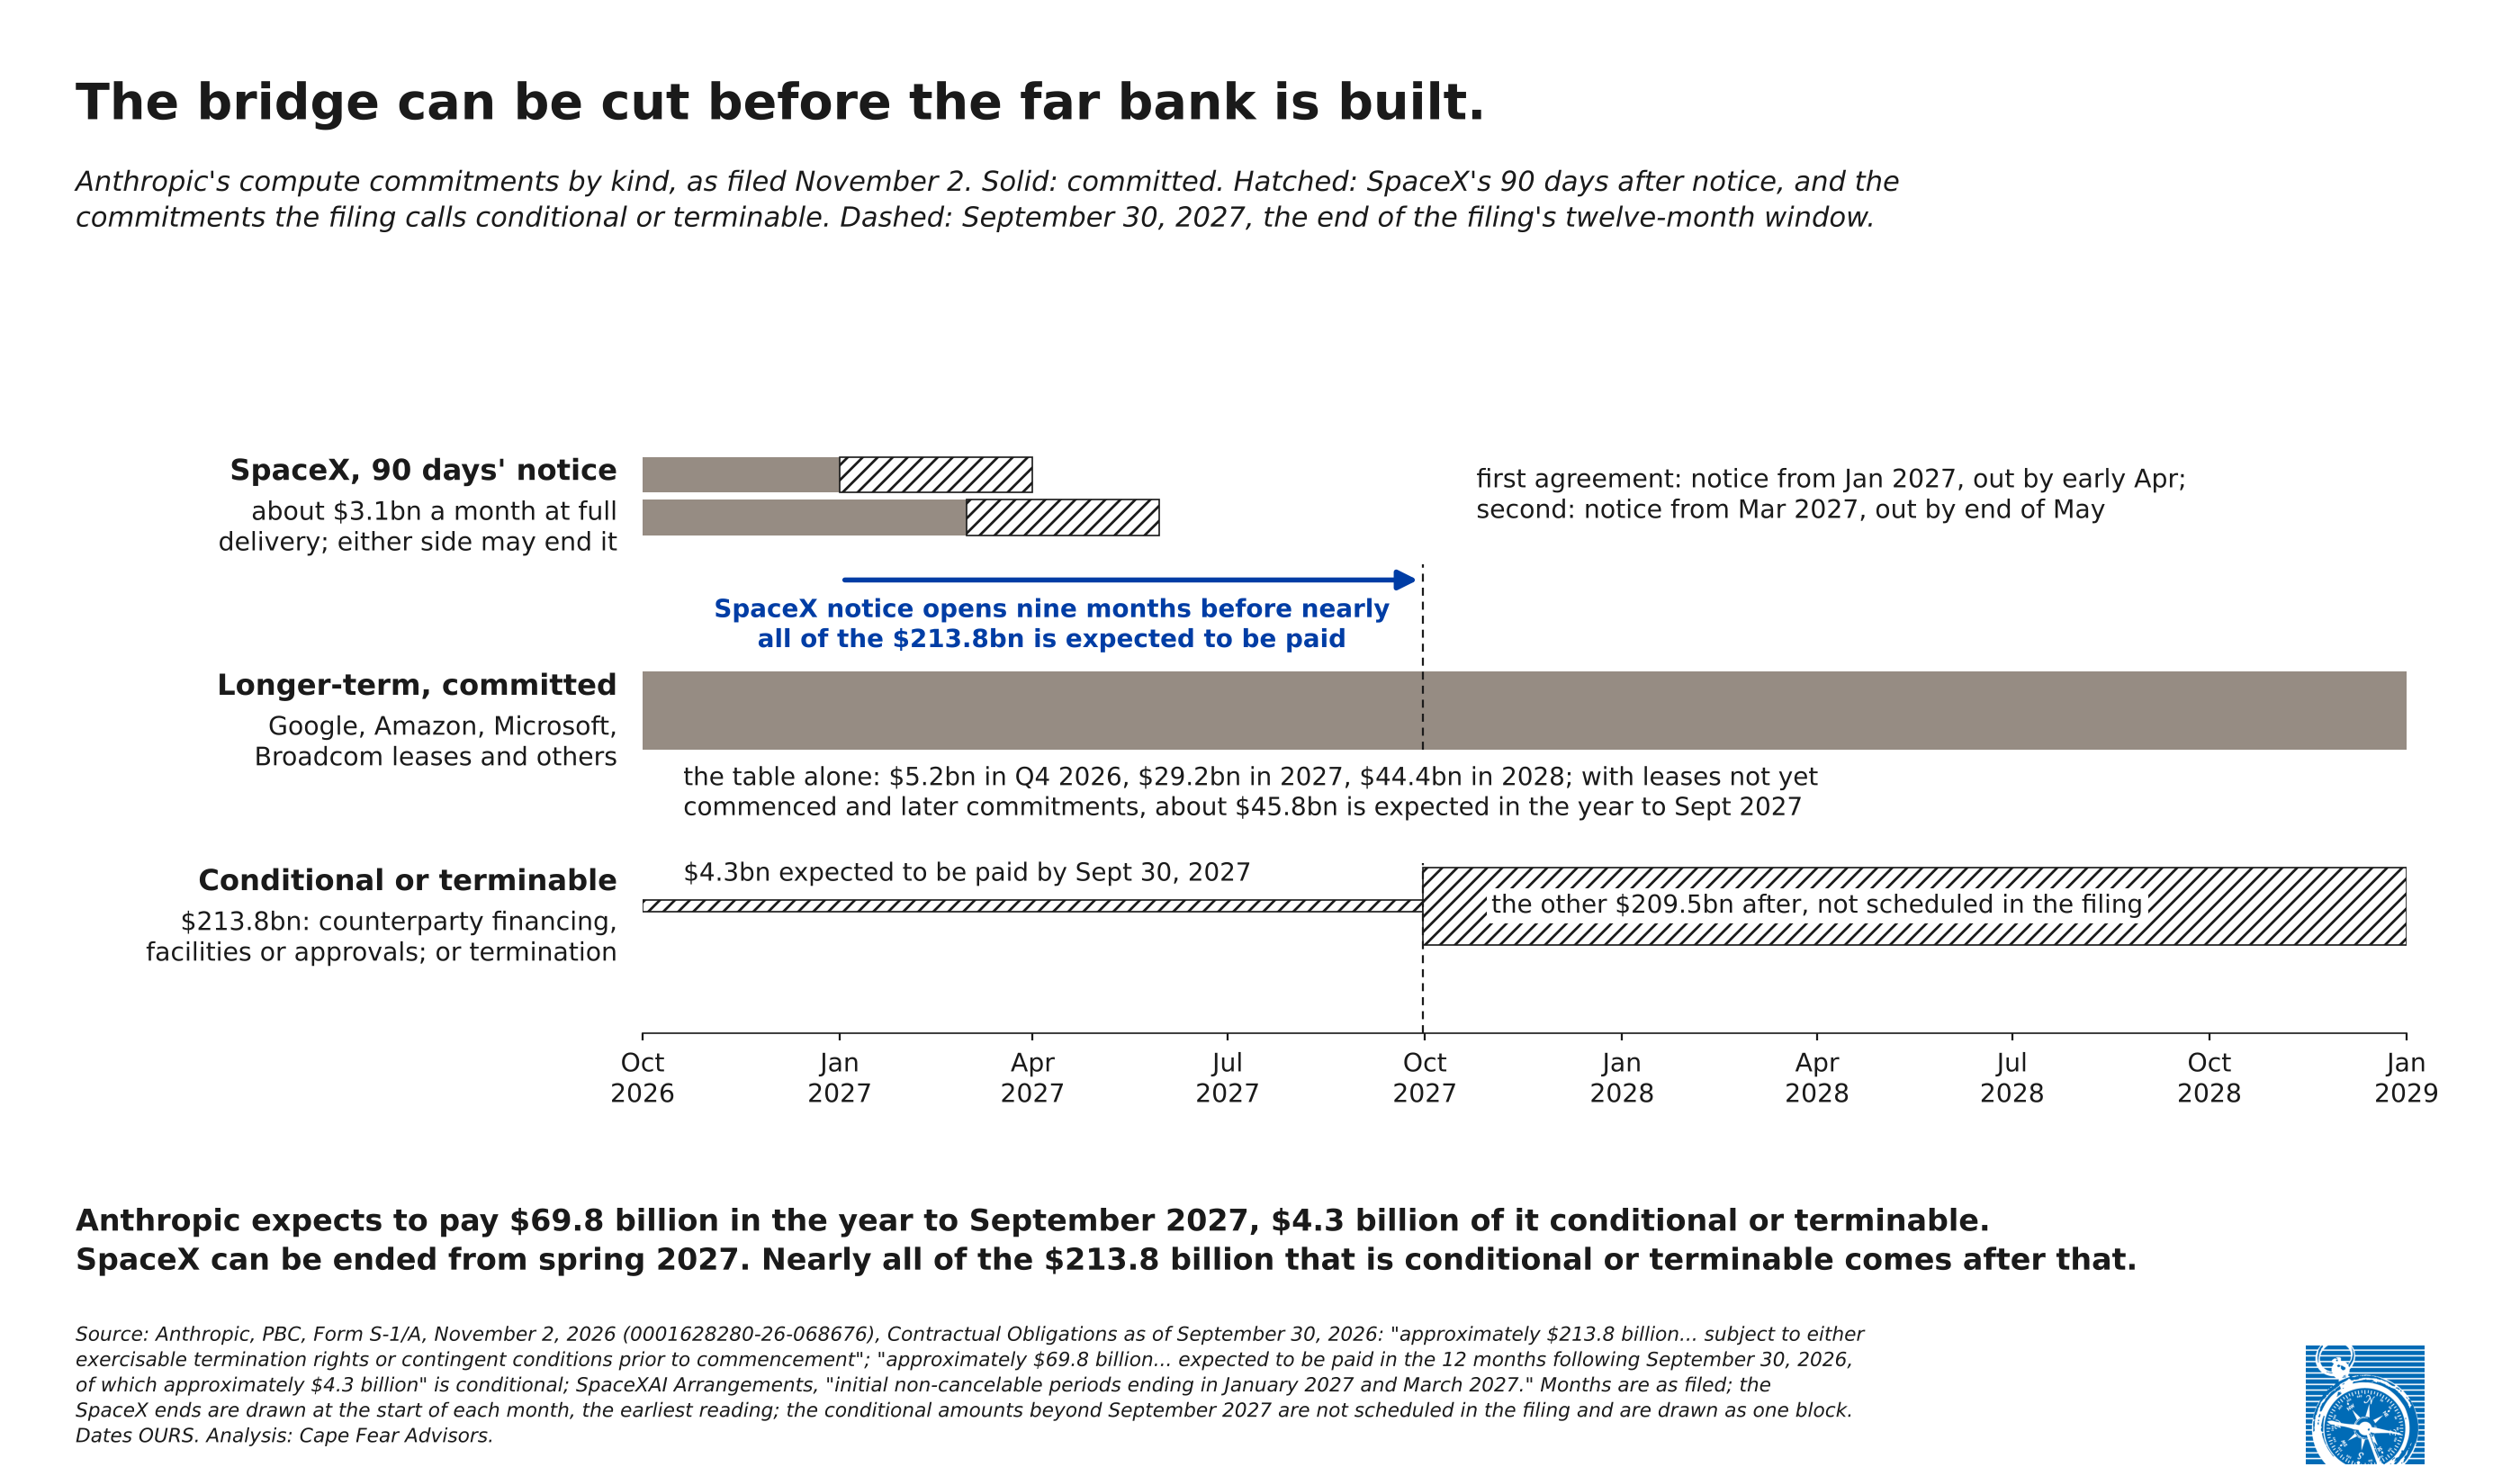
Our reading, stated as an assumption: the SpaceX line is the first Anthropic would let go. At about $3.1 billion a month at full delivery, it sits above the flat average of any other line Anthropic names. It is the only one either party can end on 90 days' notice, after initial periods ending in January and March 2027. And the buyer says, in both its filings, that it intends to backfill short-term compute with long-term capacity as that capacity arrives. (10)
The far bank, sized
The amendment sizes the conditional side as well. Of about $895.4 billion of commitments of every kind, about $213.8 billion "relates to arrangements that are subject to either exercisable termination rights or contingent conditions prior to commencement, such as the counterparty's ability to secure financing, facilities, or regulatory approvals." Of the $69.8 billion expected to be paid in the twelve months after September 30, about $4.3 billion, 2.0% of the $213.8 billion, falls in that bucket. (11) Nearly all of the $213.8 billion that is conditional or terminable is expected to be paid after September 2027.
A new risk factor states the exposure in the filer's words: "certain of our compute providers and infrastructure partners depend on third-party financing or credit support to acquire chips and develop capacity, and if such financing or support becomes unavailable or more costly, contracted capacity may be delayed, repriced, reduced, or not delivered." (12) AMD's commitment now lists among its conditions "certain pricing, financing and other purchase and capacity terms." Nscale's carries a "best efforts" obligation to obtain financing, and $34.9 billion of the Lambda commitment ends if Lambda does not secure its facility lease. (13)
On October 25 Elon Musk wrote on X that "debt markets have almost entirely shut off access to money for any company that doesn't have substantial revenue independent of AI data centers," and that "the 200+ neoclouds are going to see guppy-level death and consolidation." (14) If the market is as the post describes, the conditions on the far bank are harder to meet, and the line either party can end on 90 days' notice is the one that stays. The same week, on our record, North Star's $63 billion vehicle for Anthropic's Broadcom equipment found lenders with Broadcom's guarantee behind most of it, and SpaceX signed a $40 billion GPU lease commitment on its own credit. (15) The market was open to borrowers with their own credit, or a supplier's, behind the debt.
Two calendars
The twelve-month figure makes the calendar testable. Of the $69.8 billion expected to be paid by September 2027, about $24.0 billion is short-term: $17.4 billion at September 30 and $6.6 billion entered into after it. That leaves about $45.8 billion of longer-term commitments for the year. (16)
Against it, the two paths from "The Growth Gap," at the compute share of revenue the filings show for the second and third quarters, 48 to 58 cents on the dollar:
- on the slowdown path, $81.7 billion of revenue needs about $39.2 billion to $47.4 billion of compute;
- at the third quarter's pace, $193.6 billion needs about $92.9 billion to $112.2 billion. (17)
On the slowdown path, the longer-term commitments expected to be paid in the next year come to about the compute the path needs. At the third quarter's pace they cover under half, and the bridge carries the rest. The filer's own expectation sits on the second side: "We expect our use of short-term compute to continue to increase in the near term." In October the sentence read "to increase." (18)
The construction has soft ground, named here. The commitments are minimums, and their timing "may differ" as capacity is delivered. The compute share includes training and research, and it fell through the first half before the third quarter's short-term compute raised it. (19)
Two kinds of collateral
The far bank and the bridge are financed in different ways, and the terms on each side match the collateral behind it.
A neocloud raises money against two things: the GPUs, and the customer's contract. The customer's credit sets the price of the second. IREN finances its Microsoft deployment at 7.05% to 7.12%, and its "non-investment-grade customer deployments" at 9.0%. CoreWeave's indenture lets it borrow against its OpenAI contract at 75% of value, rising to 90% if OpenAI carries an investment-grade rating. Nebius states that cash flow from its Microsoft agreement "will be utilized to finance part of the capital expenditure associated with the Agreement." (20) A lender advances against a contract that runs long enough to repay the loan. The neoclouds' hyperscaler contracts on file run five years or more and, where the filings say, end for cause, failed delivery or insolvency. (21)
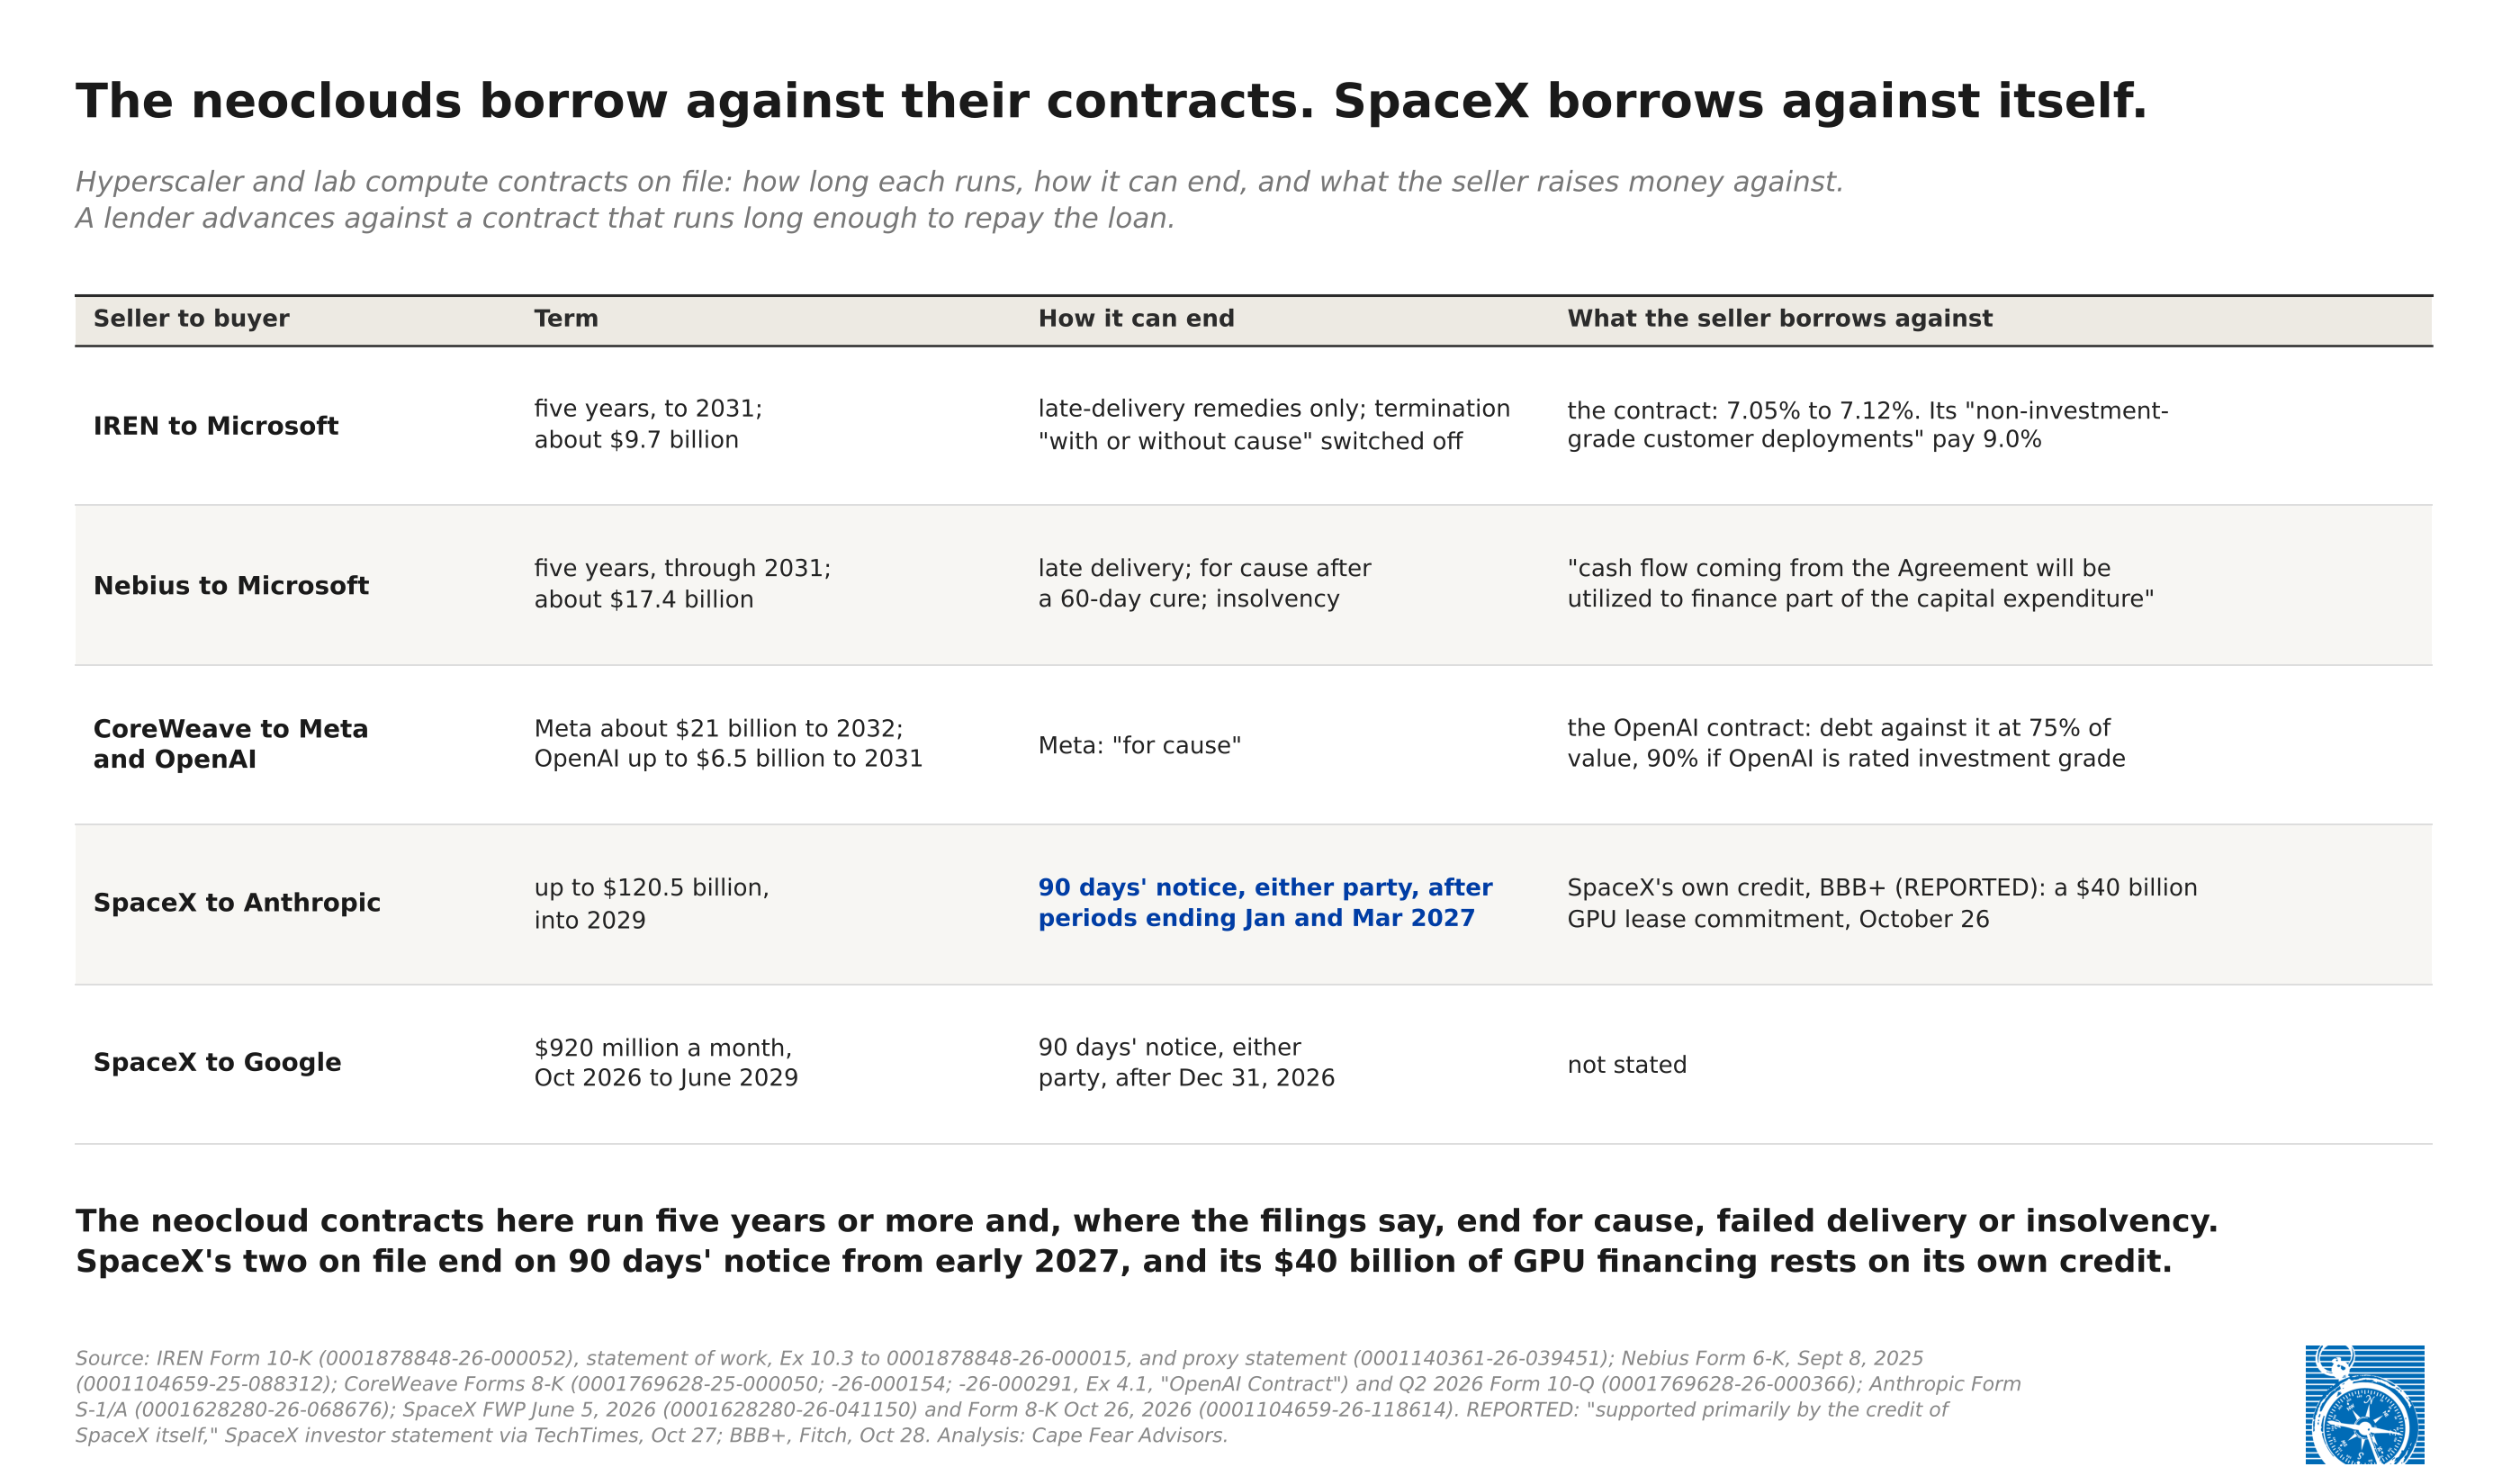
SpaceX raised its $40 billion on the other kind of collateral. The GPU lease commitment it filed in October rests, as reported, "primarily" on the credit of SpaceX itself, rated BBB+, with Starlink and launch revenue behind it. (22) No financing against the Anthropic contract is on the record, and the contract carries a 90-day exit.
The replacement capacity is financed the neocloud way, and the contract it would be financed against is Anthropic's. The S-1/A states no credit rating for Anthropic; its revolving credit agreement releases its security if Anthropic obtains an investment-grade rating. The Financial Times reported in October that Anthropic expects a rating in the double-B range. (23) The condition on the far bank therefore runs through two balance sheets: the builder's access to capital, and the credit of the contract the builder borrows against.
Next week's piece reads every seller of compute to a lab or a cloud the same way, and two of its findings belong here. First, by the test the filings allow, a company that rents compute to another company that resells cloud is acting as a neocloud, and SpaceX rents to Google: $920 million a month from October 2026 to June 2029, cancelable by either party on 90 days' notice after December 31, 2026, disclosed by free writing prospectus two days after SpaceX's last amendment and absent from its final prospectus. (24) Second, among the sellers we have read for whom an AI contract is material, every one puts it on its record by name: Nebius, CoreWeave, IREN, Nscale, Akamai, TeraWulf, Hut 8. SpaceX letters its largest customer and files none of the agreements as exhibits. Its stated reason is the exit clause. (25)
Who blinks, and who files
The clause runs both ways, and Musk said so first. On May 28 he described the arrangement as a lease with a mutual 90-day cancellation, wrote that "the short term was our request, not Anthropic's," and added, "We won't leave them hanging and will provide a reasonable off-ramp." (26) The amended terms keep the exit mutual, and the record gives each side its own view of the window.
- Anthropic can leave a line its own filing says "currently costs significantly more" than its multi-year compute, once the backfill arrives.
- SpaceX told investors in June that the structure allows it to monetize capacity "while still permitting reallocation of that capacity for our own internal initiatives if needed in the future." SpaceX's contract with Google carries its own 90-day clause, open after December 31, 2026, in the same window. (27)
On the record, a notice can reach the market without a current report. SpaceX told the Commission's staff in June that the agreements are ordinary-course contracts outside the exhibit rule. (28) Anthropic's exhibit index, read Monday, files one compute agreement, the master equipment lease with Broadcom, and no agreement with SpaceX, Google, Amazon or Microsoft. (29) On both filers' treatment, the first record of a notice is likely a periodic report. Both companies' first annual reports fall due after the January window opens, and whichever files first is where a January notice could first appear. After them come the first-quarter reports in May: Customer B's share at SpaceX, and whether Anthropic sizes its short-term compute again.
These are updates, as "The Growth Gap" framed them, not falsifiers. A short-term figure falling toward zero by mid-2027, with Customer B's share falling with it, reads as the slowdown path or as SpaceX taking the capacity back. A short-term figure above $5.0 billion a quarter reads as demand still ahead of the long-term capacity.
One question from "One Relationship, Two Records" stays open. That piece said the blank obligations table was the first place the SpaceX total's end date could print. The table now prints by year, but it carries only non-cancelable commitments "with a remaining term in excess of one year." The SpaceX agreements' non-cancelable periods end within a year of September 30, which appears to place them, on the table's stated definition, outside it, among the short-term commitments: $17.4 billion at September 30, and $24.0 billion with the short-term agreements entered after it. On our assumptions, the SpaceX payments Anthropic could not avoid at September 30 come to roughly $12 billion to $17 billion through the non-cancelable periods, or $22 billion to $26 billion with the 90-day notice periods that follow them. (30) The buyer's own schedule appears to classify the line as short-term.
The sensitivity we flagged, still open
On October 30 we added a dated comment to "The Growth Gap." The filing ties its stepped-up enforcement against usage-policy violations "in particular in August and September 2026" to an uncertain effect on revenue and revenue growth. If violating revenue ran at a steady share through the second quarter and stopped from August, third-quarter growth on compliant revenue was about 55% to 58%, not 46.7%, and the slowdown path's next year runs about $86 billion to $89 billion. (31) The amendment repeats the nine-month estimate without a quarterly split, so the test stays where the comment left it. Across that range the slowdown path needs about $41.2 billion to $51.6 billion of compute, from inside the $45.8 billion of longer-term commitments to about $5.8 billion above them, a margin the construction above leaves unresolved.
What changes this
Each filing above updates the calendars. What moves the reading is whether the far bank gets built on time. Capital is the first condition, and the record of the last two months shows it tightening for some of the builders:
- Nscale's registration statement of September 18 is unamended, and NVIDIA is reported to be negotiating the financing of its West Virginia site. Its Anthropic agreements carry the best-efforts financing clause. (32)
- SB Energy's offering, building for OpenAI with NVIDIA's guaranty capped at $105 billion behind the leases, was reported postponed in September. (33)
- CoreWeave's unsecured notes traded to yields above 15% in October, and its credit default swaps reached a record. (34)
- Lambda cut its pre-IPO valuation target, and its largest Anthropic agreement ends if it does not secure its facility lease. (35)
Power and permits are the second, and the filing names both: the conditions on the $213.8 billion include "facilities, or regulatory approvals," and a risk factor new to the amendment says "the lead times required to build new generation capacity, transmission infrastructure, and grid interconnections can extend for years." (36) Oracle's build for OpenAI shows the same calendar from the builder's side. Its Abilene campus is delivering, and the other four Stargate campuses each wait on some combination of gas supply, transmission approvals and commissioning. Oracle told investors its guidance absorbs a delay of up to two quarters at any large site, and the gas line to its New Mexico campus has moved its in-service target from August 2026 to February 2027, with its federal approvals still pending. (37)
If capital tightens or power slips for the builders, the conditional capacity arrives later, and the line either party can end on 90 days' notice carries more of the load, for longer, unless SpaceX gives notice first. If both hold, the backfill arrives on schedule, and the bridge can be cut. The builders' filings, on financing and on power alike, are where the answer is likely to show first.
Free to read, no paywall. Readers who find the work useful can support it at the foot of the page; payment offsets the time and buys no access. Corrections run in daylight, dated, in a comment or in the following piece, and a reader who finds one is doing us a favor.
Standing Disclosure
Cape Fear Advisors holds no direct position, long or short, in the securities discussed here. Any exposure is indirect, through managed funds it does not control, which may include index funds holding the public companies named.
Anthropic, the subject of this piece, is the developer of Claude, which we use in preparing our work. That nearness cannot be checked away, which is why no claim here rests on trust in the tool: every figure carries a public source and every derived figure carries its inputs in the notes. Others named here have ties to Anthropic: SpaceX is its compute supplier under the agreements read here; Google and Amazon are investors and compute suppliers; Microsoft is a compute supplier; AMD, Nscale, Lambda, Akamai, TeraWulf, Hut 8 and Broadcom supply or finance its compute. NVIDIA, Nebius, CoreWeave, IREN and SB Energy are named as builders and financiers of capacity in the same market. Companies not named here may hold positions or supply relationships that bear on the filers discussed, which is part of why every piece is re-checked against the filings each time. Figures are quoted from the filers without characterization, and the same standard of reading is applied to every filer named.
Notes
[1] FILED. Anthropic, PBC, Form S-1/A, accession 0001628280-26-068676, accepted November 2, 2026 at 14:24 UTC, Quarterly Consolidated Statements of Operations: revenue $16,956 million for the three months ended September 30, 2026; nine months $33,242 million. EDGAR re-run at 17:30 UTC November 2, 2026, before posting: the S-1/A is the latest filing on the docket.
[2] FILED and OURS. Anthropic, Form S-1, accession 0001628280-26-067168, October 26, 2026, Business ("86 times"). Our band and point are from "Anthropic, First Read," October 26, 2026. $16,956 million less $16,942 million is $14 million.
[3] FILED; OURS. $16,956 million less $11,555 million is $5,401 million; $11,555 million less $4,731 million is $6,824 million.
[4] OURS on FILED. The slowdown path keeps 32.4% of the prior quarterly growth rate each quarter (46.74% over 144.24%), as constructed in "The Growth Gap": $19,524 million, $20,483 million, $20,808 million and $20,916 million, $81.7 billion in total. The third quarter's pace, 46.74% a quarter, gives $193.6 billion. Printed October 29: $81.6 billion and $193.0 billion, on the estimated quarter.
[5] FILED. S-1/A, Management's Discussion and Analysis, Components of Results of Operations, Revenue: "approximately 5% to 7% of our revenue for the nine months ended September 30, 2026." The October 26 filing carried the same range.
[6] FILED. S-1/A, Management's Discussion and Analysis, Our Financial Model and Key Factors. The October 26 filing: "which typically carries a higher cost per unit of compute." Neither filing names the provider.
[7] FILED; OURS. S-1/A, quarterly statements: compute and infrastructure $9,863 million (third quarter) and $5,558 million (second); revenue $16,956 million and $11,555 million. 9,863 over 16,956 is 0.582; 5,558 over 11,555 is 0.481; both floored to the cent. Growth, OURS on the same figures: compute 77.46%, revenue 46.74%, floored to the tenth. Operating loss and Adjusted Operating Margin: S-1/A, Management's Discussion and Analysis, quoted.
[8] FILED. S-1/A and S-1, Liquidity and Capital Resources; the sentence is the same in both. "Anthropic Direct" appears eight times in each, and the defining paragraph is unchanged.
[9] FILED and REPORTED. Space Exploration Technologies Corp., Form 10-Q for the quarter ended September 30, 2026, accession 0001628280-26-066880, Concentration of risk: Customer B 34.5% of revenue of $14,575 million, Customer A 16.6%. OURS: $5,028 million. REPORTED: Bloomberg, October 29, 2026. Neither company's filings name the other in this connection.
[10] FILED and OURS. S-1/A, Infrastructure Service Arrangements: "approximately $3.1 billion in the aggregate per month once all capacity has been delivered, which we expect in December 2026"; "Following initial non-cancelable periods ending in January 2027 and March 2027 under the respective agreements, each agreement may be cancelled by either party upon 90 days' advance written notice." Unchanged from October 26. The ranking of monthly lines is ours, against the flat averages of the other named lines (Google $1.30 billion, Amazon $0.92 billion, Microsoft $0.57 billion, and Broadcom $2.69 billion, $161.2 billion over 60 months, if all five-year leases ran at once). The assumption that this line goes first is ours.
[11] FILED; OURS. S-1/A, Contractual Obligations, as of September 30, 2026. The filing describes the bucket in two sentences, with the terms in opposite order. First: "Approximately $213.8 billion of the aggregate total of our contractual obligations relates to arrangements that are subject to either exercisable termination rights or contingent conditions prior to commencement, such as the counterparty's ability to secure financing, facilities, or regulatory approvals, as applicable." Second: "Approximately $69.8 billion of our aggregate contractual obligations are expected to be paid in the 12 months following September 30, 2026, of which approximately $4.3 billion relates to arrangements that are subject to either contingent conditions or termination rights prior to commencement as described above." The $4.3 billion is the twelve-month portion of the whole $213.8 billion, both kinds; the filing does not split the two. 4.3 over 213.8 is 2.0%.
[12] FILED. S-1/A, Risk Factors. A search of the October 26 filing for "third-party financing or credit support" returns nothing (November 2, 2026, whitespace normalized).
[13] FILED. S-1/A, Infrastructure Service Arrangements: AMD Hardware Supply Agreement; Nscale Services Agreements; Lambda Agreements.
[14] REPORTED. Elon Musk on X, October 25, 2026, 3:11 pm, a reply to @chamath, read at source November 2, 2026. The post also says "SpaceX closed $40B of debt for GPUs"; the filed instrument is a commitment letter (note 15).
[15] REPORTED and FILED. North Star: The Wall Street Journal, October 27, 2026. SpaceX: Form 8-K, accession 0001104659-26-118614, October 26, 2026, Item 8.01, a commitment letter for a GPU finance lease of about $40 billion.
[16] FILED; OURS. S-1/A, Contractual Obligations: "Approximately $69.8 billion of our aggregate contractual obligations are expected to be paid in the 12 months following September 30, 2026"; short-term commitments "approximately $17.4 billion as of September 30, 2026"; short-term agreements after September 30, "approximately $6.6 billion." The aggregate includes both short-term amounts: "the contractual obligations in the table below plus the short-term and subsequent commitments, as well as leases not yet commenced... are approximately $895.4 billion," and the table's $319,993 million plus $17.4 billion, $451.2 billion, $100.2 billion and $6.6 billion is $895.4 billion. OURS: $69.8 billion less $24.0 billion is $45.8 billion. The $45.8 billion is wider than the table: it also carries the twelve-month portions of leases not yet commenced and of subsequent commitments, which the filing does not split. The table's own rows (Q4 2026 $5,231 million; calendar 2027 $29,165 million) cover only the table. Short-term commitments have a remaining term of one year or less by the filing's definition, so all fall within the twelve months.
[17] OURS. Path revenue per note (4), times 0.48 and 0.58 per note (7); compute requirements floored to the tenth ($47.40 billion, $112.28 billion).
[18] FILED. S-1/A and S-1, Management's Discussion and Analysis, Our Financial Model.
[19] FILED. S-1/A, Contractual Obligations: "the timing of our payments, and in some cases the amounts, may differ from those shown." Quarterly compute share: 0.71 in the first quarter of 2026 (3,387 over 4,731, floored), 0.48 in the second, 0.58 in the third, OURS on the filed quarterly statements.
[20] FILED and FURNISHED. IREN Ltd, Form 10-K for the fiscal year ended June 30, 2026, accession 0001878848-26-000052: the Microsoft GPU financing, effective rates 7.05% and 7.12%. The Mackenzie financing, "GPU backed financing for non-investment-grade customer deployments... at a 9.0% fixed rate": IREN proxy statement, Form DEF 14A, accession 0001140361-26-039451 (FILED), and the fiscal 2026 results release, accession 0001878848-26-000051 (FURNISHED). CoreWeave, Form 8-K, accession 0001769628-26-000291, June 18, 2026, Exhibit 4.1, definition of "OpenAI Contract" and the permitted debt provisions. Nebius Group N.V., Form 6-K, accession 0001104659-25-088312, September 8, 2025.
[21] FILED and OURS. Nebius and Microsoft: five-year term, termination for delivery failure, for cause after a 60-day cure, or on insolvency (6-K, note 20). Nebius and Meta: five-year orders, termination for delivery failure (6-Ks, accessions 0001104659-25-109803 and 0001104659-26-027886). CoreWeave and Meta: "Either party may terminate the MSA (and any order thereunder) for cause" (8-K, accession 0001769628-25-000050, Item 1.01; 8-K, accession 0001769628-26-000154, Item 8.01). IREN and Microsoft: the statement of work disapplies the purchase-order termination "with or without cause" (Exhibit 10.3 to accession 0001878848-26-000015). The connection between term and advance is our reading of these instruments together.
[22] FILED and REPORTED. Form 8-K per note (15). "Supported primarily by the credit of SpaceX itself": SpaceX's investor statement as carried by TechTimes, October 27, 2026. BBB+: Fitch, as reported October 28, 2026.
[23] FILED (probe) and REPORTED. A search of the S-1/A, whitespace normalized, for "Moody," "S&P," "Standard & Poor," "Fitch," "KBRA," "Kroll," "credit rating" and "investment grade" (November 2, 2026, 17:1x UTC) returns only the A&R Credit Agreement's release of guarantees and security "on and after the date we have obtained an Investment Grade Rating... from at least two out of three of Moody's, S&P, and Fitch," and its rating-based pricing after that date. No rating of the registrant is stated. The Financial Times, October 2026, as read October 30, 2026; not read at source.
[24] FILED. SpaceX, free writing prospectus, accession 0001628280-26-041150, June 5, 2026, 18:41 UTC, after Amendment No. 2 of June 3 (0001628280-26-040364). Final prospectus, Form 424B4, accession 0001628280-26-042639, June 12, 2026: "Cloud Service Agreement" appears zero times; "Google LLC" appears once, in a director's biography (searched November 2, 2026). The test is ours.
[25] FILED and OURS. Nebius (note 20); CoreWeave (note 21); IREN, Form 8-K, accession 0001140361-25-040072, Item 1.01; Nscale, Form S-1, September 18, 2026; Akamai, TeraWulf and Hut 8 as recorded in our October 27 ledger. SpaceX: Form 10-Q per note (9); correspondence per note (28). Materiality to the seller is our judgment on each filer's revenue.
[26] REPORTED. Posts on X by Elon Musk, May 28, 2026, as reported by Yahoo Finance, June 1, 2026; not read at source.
[27] FILED and OURS. SpaceX 424B4 per note (24), Business. Google terms per note (24). The two contracts' prices differ: on our October 25 figures ("Adding It Up: The $40 Billion Gigawatt"), Google pays $11.46 a GPU-hour against Anthropic's $5.27, OURS on FILED terms.
[28] FILED and OURS. SpaceX correspondence of June 1, 2026, accession 0001628280-26-039278. The inference to periodic reports: Item 1.02 of Form 8-K reaches the termination of a material definitive agreement, which Item 1.01 defines as one not made in the ordinary course of business; on SpaceX's stated position, and on Anthropic's exhibit treatment (note 29), the SpaceX agreements are not that. Both companies report on a December year-end, and no first annual report on either calendar falls due before February 2027.
[29] FILED. S-1/A, Exhibit Index, read November 2, 2026: Exhibit 10.11, Master Equipment Lease Agreement between AI Infrastructure OpCo II, LLC and Broadcom Inc., dated March 31, 2026. The note purchase and facility agreements with Amazon, Broadcom and Google (Exhibits 4.3 to 4.5) are financing instruments.
[30] FILED and OURS. S-1/A, Contractual Obligations, footnote 3 to the table: "non-cancelable purchase commitments with a remaining term in excess of one year"; short-term commitments "cancelable without penalty within one year or amounts under agreements with a remaining contractual term of one year or less," about $17.4 billion at September 30, plus about $6.6 billion of short-term agreements after it. The filing does not list which agreements sit in the short-term amounts. OURS, the construction, on Anthropic's figures: the third quarter's $5.0 billion of short-term compute is about $1.67 billion a month (FILED; SpaceX's Customer B gives $1.68 billion, per note 9). From there, October and November ramp from about $2.0 billion to $3.1 billion a month ($4.5 billion to $6.2 billion); December onward runs at $3.1 billion, with the March agreement carrying a third to two-thirds of the rate. Through the end of the non-cancelable periods (January and March 2027): $12.8 billion to $16.5 billion, printed outward as roughly $12 billion to $17 billion. With the 90-day notice periods that can begin only after them (to about April and June 2027): December onward is $3.1 billion times five months for the January agreement's share and seven for the March agreement's, $17.6 billion to $19.6 billion, for $22.1 billion to $25.8 billion in all, printed outward as roughly $22 billion to $26 billion. Which reading the filing's minimums use is not stated; both end within a year of September 30.
[31] OURS on FILED. The dated comment of October 30, 2026 on "Anthropic, Amended: The Bridge and the Far Bank"; S-1, Components of Results of Operations, Revenue. OURS: $86 billion times 0.48 to 0.58 is $41.2 billion to $49.8 billion, floored; $89 billion gives $42.7 billion to $51.6 billion; $51.6 billion less $45.8 billion is $5.8 billion.
[32] FILED (probe) and REPORTED. Nscale Ltd, Form S-1, accession 0001193125-26-395475, September 18, 2026; no amendment on EDGAR at 17:30 UTC November 2, 2026. The Wall Street Journal, October 31, 2026, on NVIDIA and the West Virginia site.
[33] FILED and REPORTED. SB Energy, Form S-1/A, accession 0001628280-26-062846, September 21, 2026: "The aggregate remedy cap is $105 billion across related guaranties on the initial 4.25 GW-IT." Postponement: IFR, September 25, 2026.
[34] REPORTED. 24/7 Wall St and TheStreet, October 2026 (yields); Bloomberg via Fortune, October 26, 2026 (credit default swaps).
[35] REPORTED and FILED. The Wall Street Journal, October 31, 2026 (valuation target). Lambda condition: S-1/A per note (13).
[36] FILED. S-1/A, Contractual Obligations (quoted at note 11) and Risk Factors. A search of the October 26 filing for "Electric grid infrastructure" returns nothing (November 2, 2026, whitespace normalized).
[37] REPORTED. Corey Trinetti, "Oracle's 5 GW Stargate Buildout: The Gap Between Power and Compute," Measured AI, November 2, 2026, citing Oracle's Investor Day of October 28, 2026 and Transwestern's filings with the Federal Energy Regulatory Commission. The Investor Day materials and the FERC docket were not read at source for this piece.
Analysis: Cape Fear Advisors.
This piece also appears on Substack. Cape Fear Advisors is an independent advisory firm based in Portsmouth, NH.
Contact Cape Fear Advisors