
The shelf has followed the two companies since spring: The $8.5 Trillion Grease Gun and The $10.25 Trillion Hypothesis in May; The Three Layer Cake the same month; The Cost of Not Beginning and The State of the Merger in July; The $430 Billion Cash Gap in August; Terafab Is Stateless on October 3; and The Hyperbole Edition on October 21. This is the update.
What the lenders wrote
On the public record, a third credit rating arrived first, the lenders signed second, the committees were described third, and the document that holds both was filed last.(1)(2)(3) The committees' formation dates are unstated.
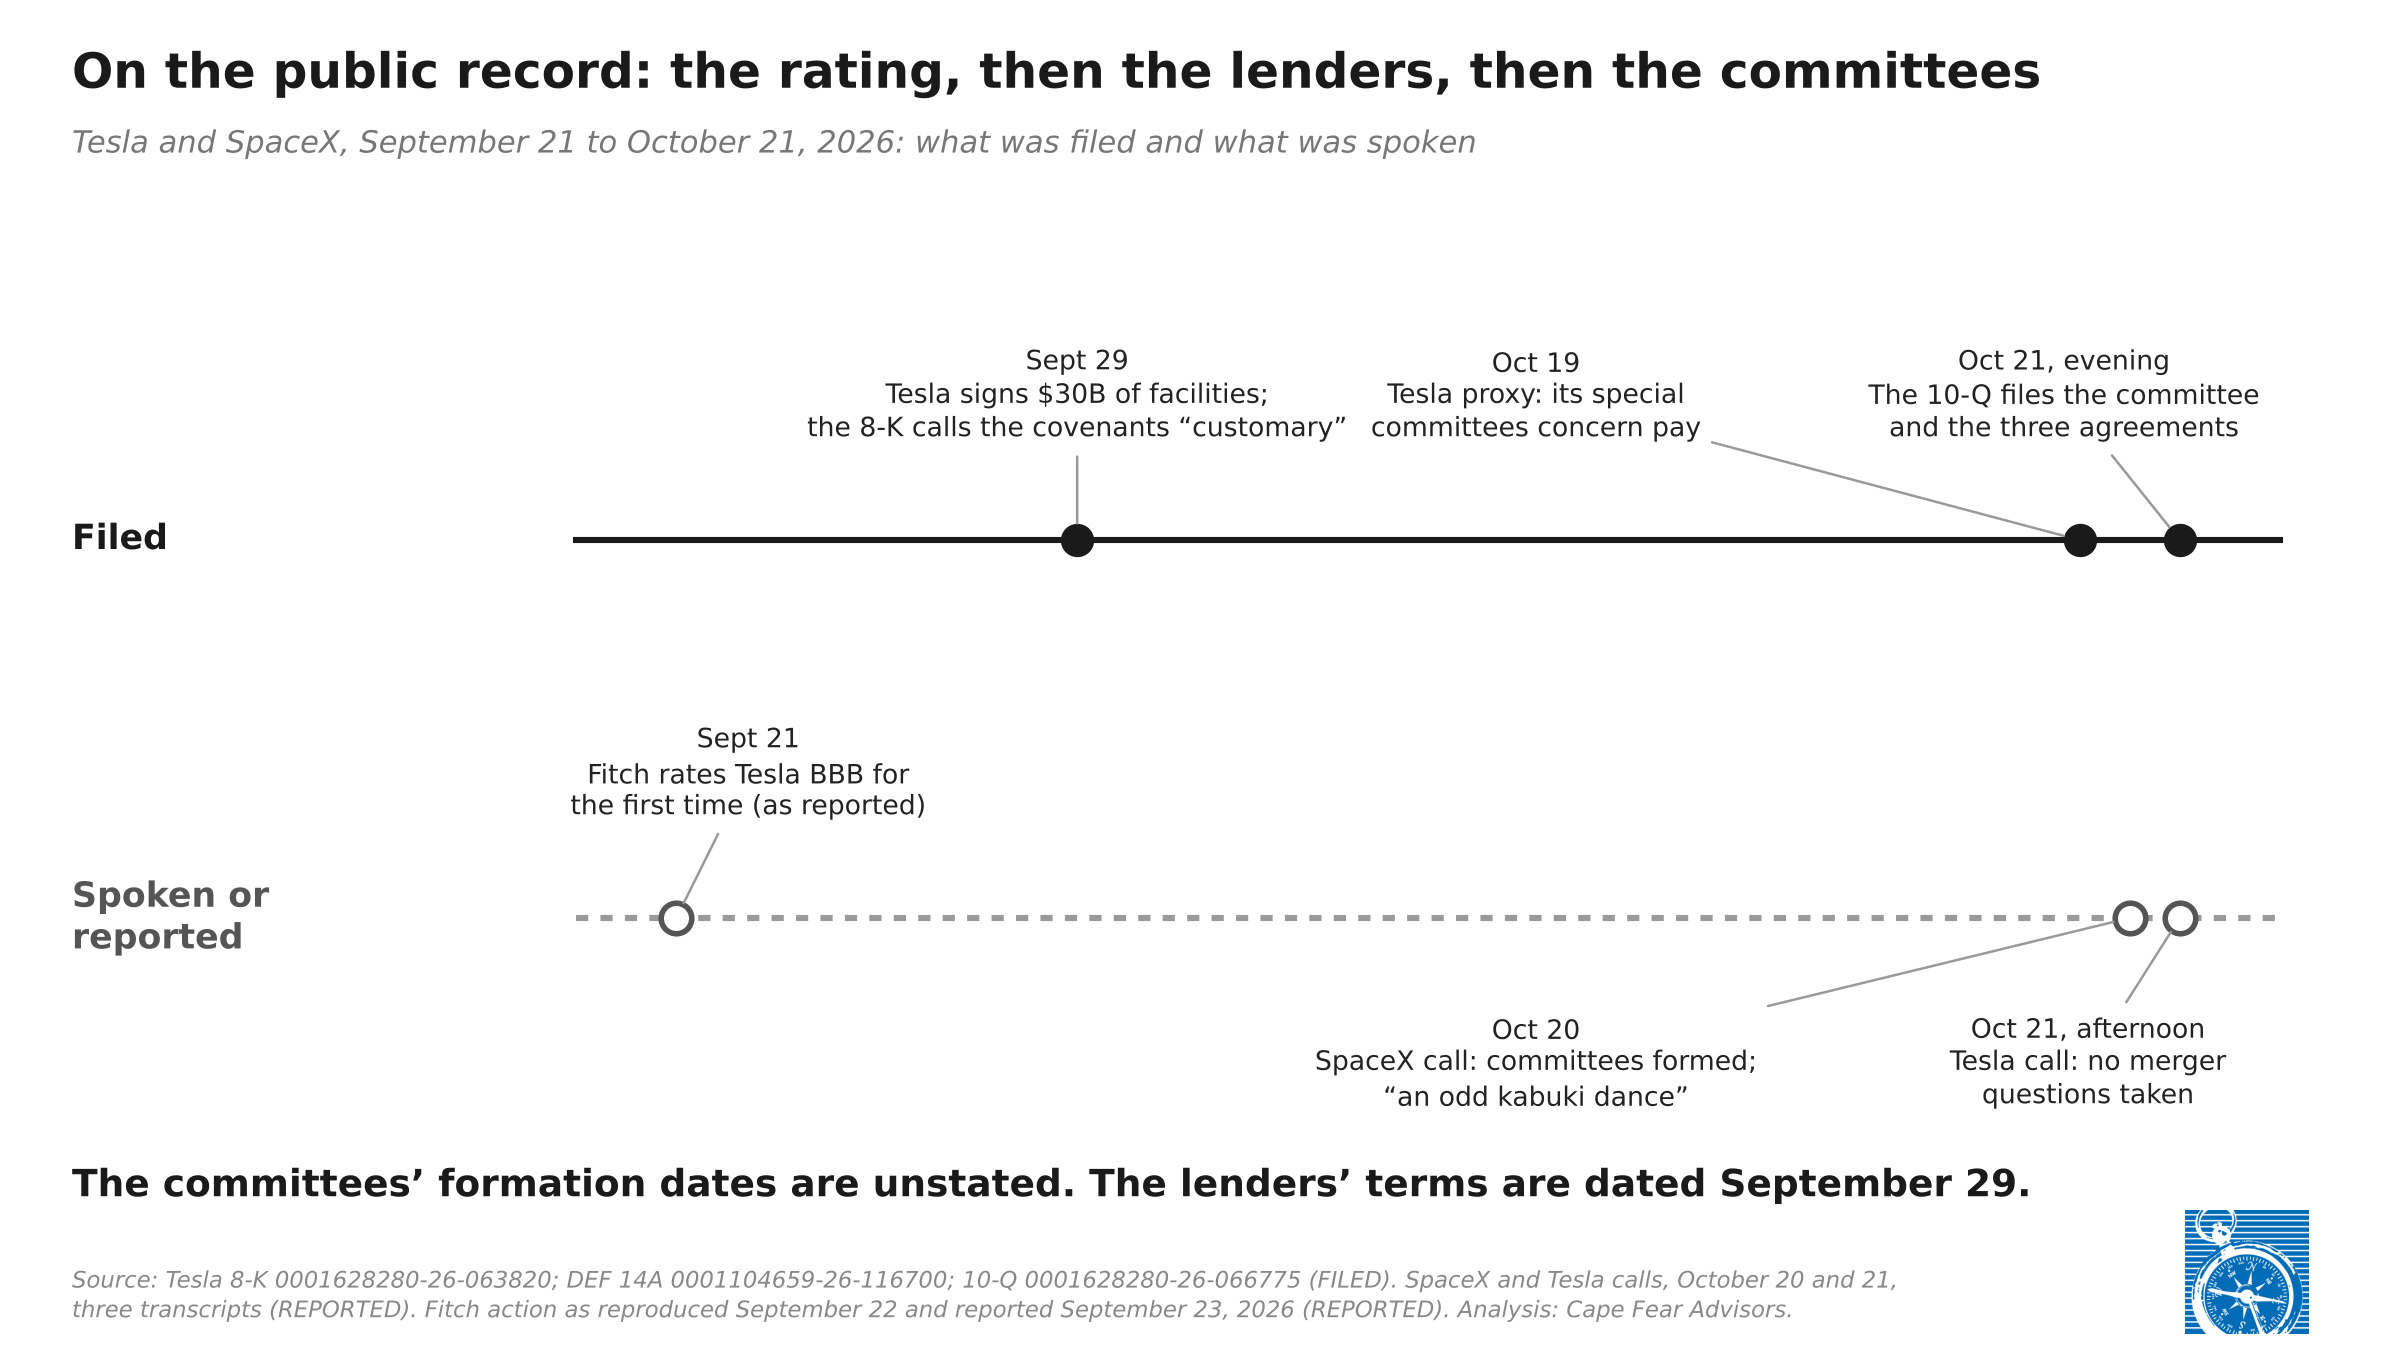
On October 20, on SpaceX's call, Musk said both boards had formed special committees of independent directors: "It's an odd kabuki dance where two groups of people are talking and I can't be in the conversation."(4) The next afternoon, on Tesla's call, he said he had said "everything that should be said yesterday," and investor relations took no questions on a merger.(5) [REPORTED] That evening Tesla's 10-Q put the committee in writing and filed the credit agreements Tesla had signed on September 29, which its current report that day had described as carrying "covenants that are customary for facilities of this type."(1)(2) [FILED]
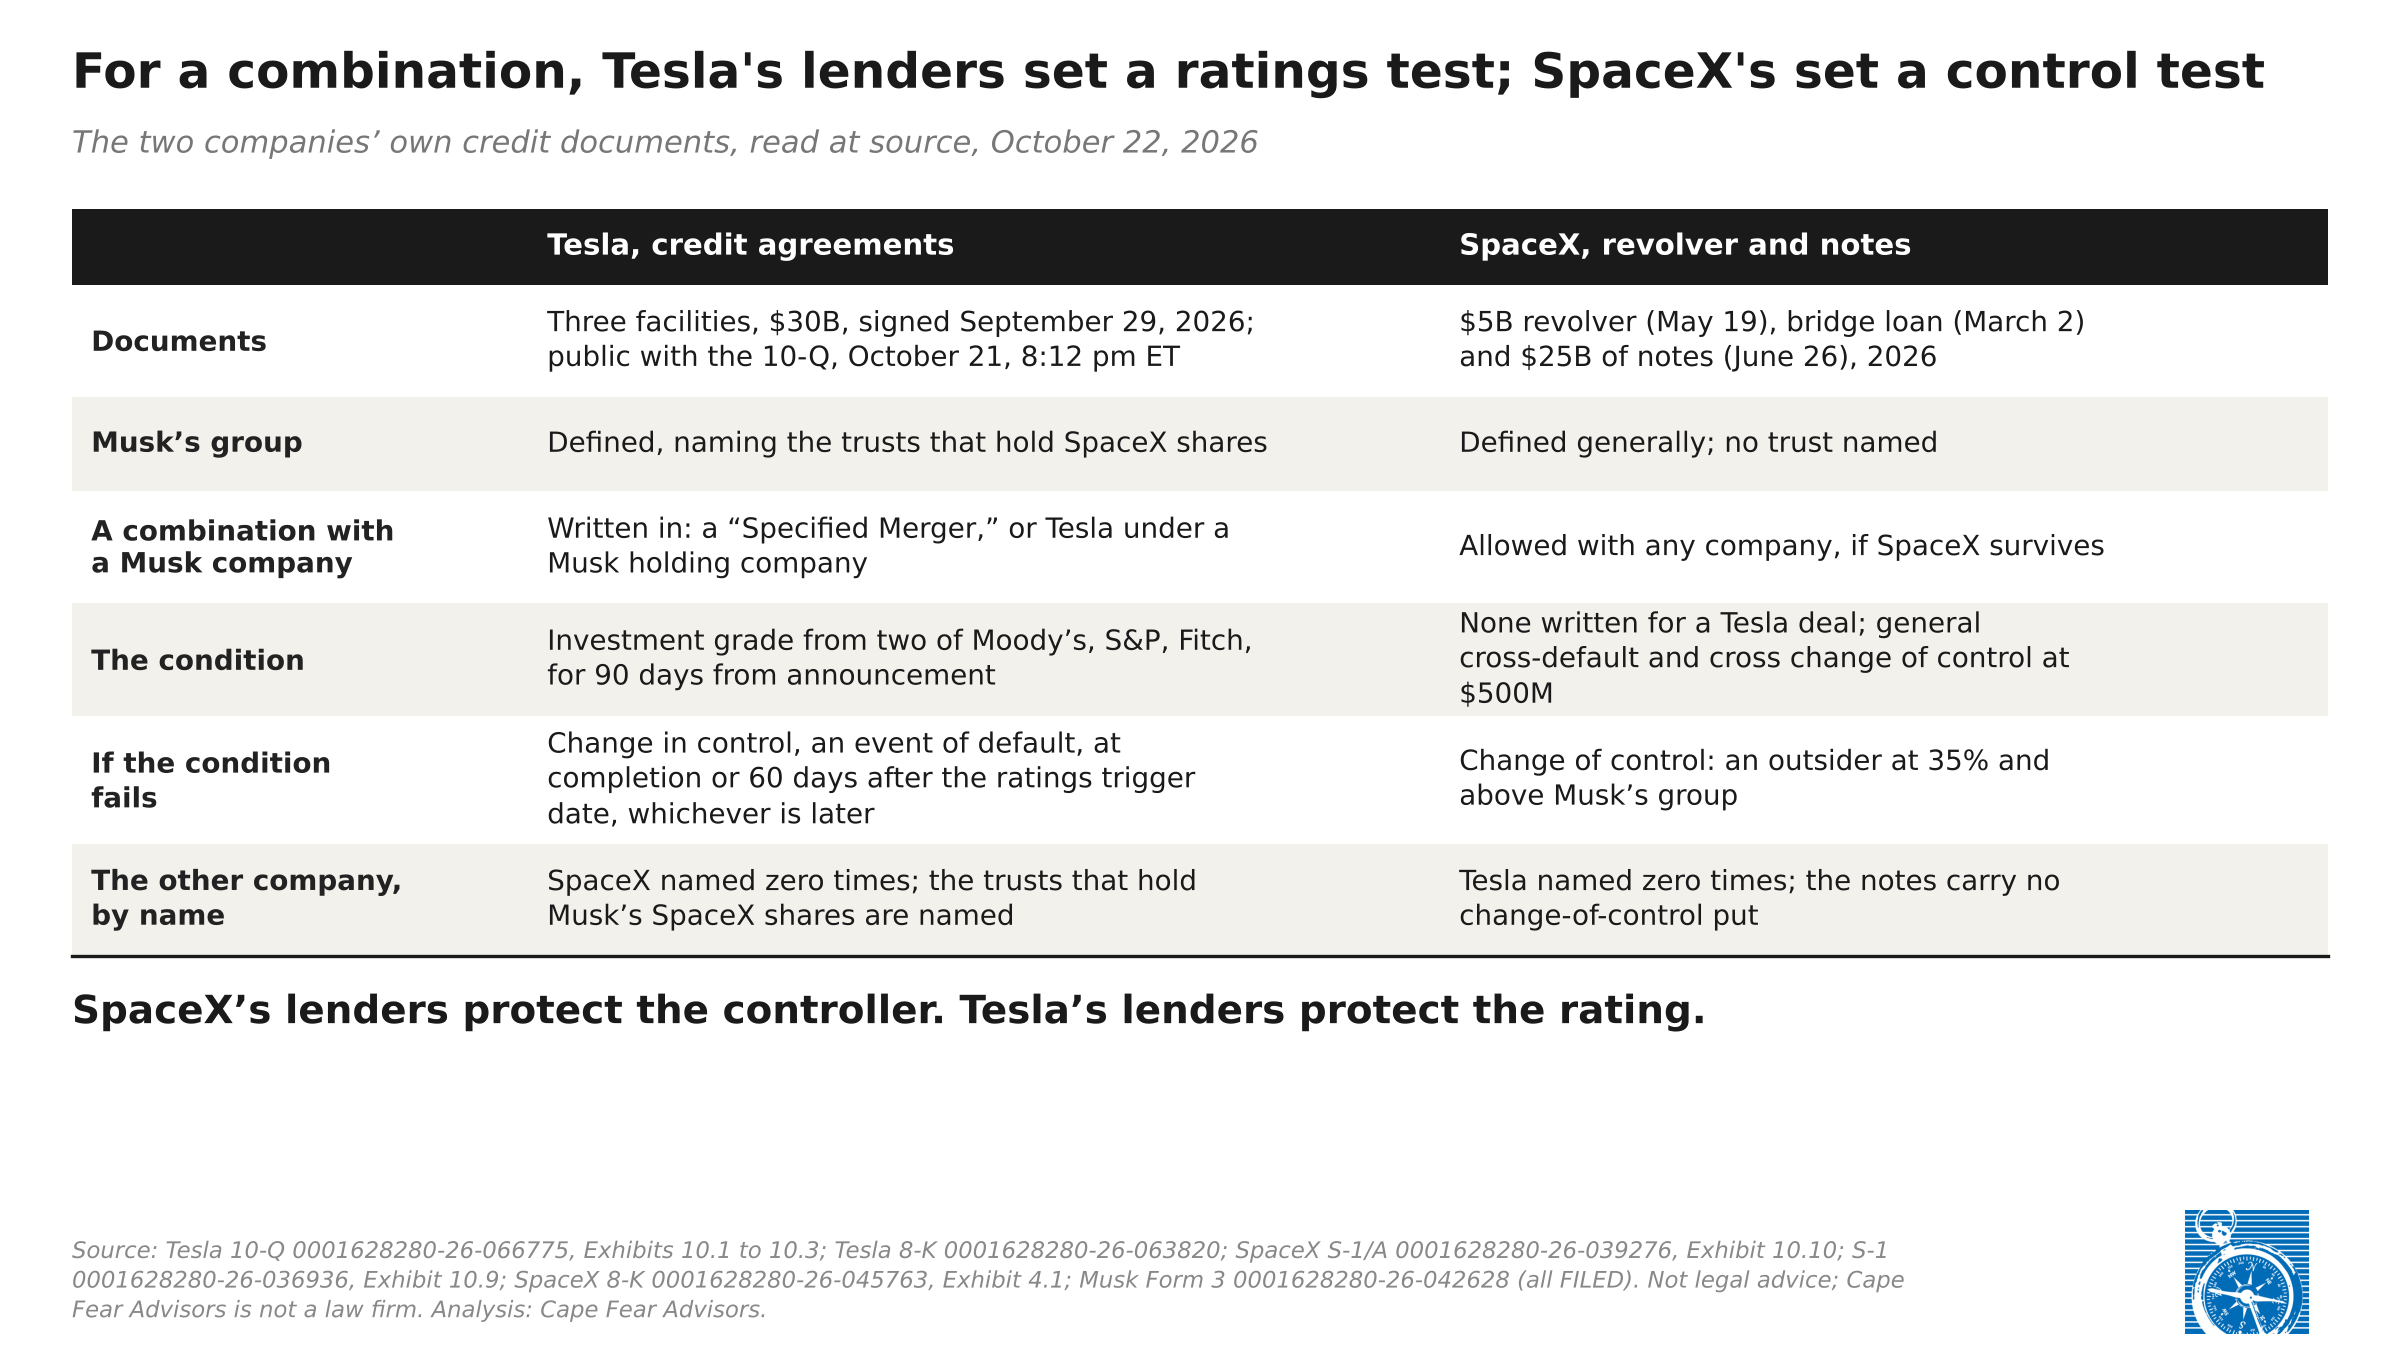
Tesla's previous revolver, from January 2023, let Musk cross half of Tesla's vote without a change in control, with no condition attached. It permitted only Tesla's own subsidiaries to merge into Tesla, so any other merger needed the lenders' consent at the time, by amendment or waiver.(6) [FILED] The September 29 agreements write a combination with a Musk company into the definitions, consent to it in advance, and attach one condition to that consent and to the carve-out.(1) [FILED] The lenders' consent moved. In 2023 they would have answered a specific deal when it came; in 2026 they answered in advance, on a rating.
- "Permitted Holder" now names "the Elon Musk Revocable Trust dated July 22, 2003, the Musk 2017 Sprinkling Trust, the Mission Trust." Musk's ownership filing at SpaceX's listing shows SpaceX shares held through those three trusts.(7) [FILED] The agreements name SpaceX zero times; they name the trusts that hold it.
- A "Specified Merger" is a combination of Tesla with an entity "owned or Controlled, directly or indirectly, by Permitted Holders." Tesla may also become the wholly owned subsidiary of a holding company they control.
- Either is permitted only if Tesla holds investment-grade ratings from two of Moody's, S&P and Fitch from the first announcement through the 90th day after it, longer while any agency has Tesla on watch or on a negative or developing outlook. If the ratings fail, the deal becomes a change in control, an event of default, at completion or 60 days after the ratings trigger date, whichever is later.
- The facilities are undrawn, so within these three agreements a failed test lets the lenders end the commitments, $30 billion of standby liquidity, rather than stopping a combination.(1)(2) [OURS]
A full-text search of EDGAR for one of the new terms, "Qualified Permitted Holder," returns three documents, and all three are these agreements.(8) [OURS]
The ratings sit close to the line. Tesla carries BBB at S&P and BBB at Fitch, the Fitch rating assigned on September 21, eight days before the agreements were signed. At Moody's it carries Baa3, the lowest investment-grade step on that agency's scale.(3) [REPORTED] The test survives one agency falling below investment grade, and Moody's is one notch from that line.
SpaceX's credit documents write no condition of their own on a combination with Tesla. We read in full its $5 billion revolver, its March bridge loan and the indenture for its $25 billion of June bonds.(9) [FILED] None of them names Tesla. The revolver treats an outsider reaching 35 percent of the vote as a change of control and lets SpaceX merge with "any other Person" so long as SpaceX survives. The bonds carry no change-of-control repurchase right. The revolver also carries general cross-default and cross change-of-control clauses at $500 million, measured including undrawn commitments.(11)
SpaceX's lenders protect the controller. Tesla's lenders protect the rating. In the structure analysts describe, an all-stock purchase of Tesla by SpaceX, SpaceX survives and Musk keeps control, so the only condition either company's lenders have written for a Musk-company combination sits on Tesla's side.(10) [REPORTED; OURS]
Where these clauses meet, the questions belong to lawyers.(11) We are not lawyers. These are hypotheticals we are not able to answer and are not attempting to.
The committee, and the person
Tesla's board "has formed a special committee... comprising disinterested directors to explore deepening Tesla's relationship with SpaceX, which could be through certain arrangements including without limitation a business combination (a "Transaction")."(1) [FILED] The mandate is wider than a merger: it reaches every tie in our July inventory, the chip plant first. The paragraph gives no formation date, no members and no advisers. SpaceX's committee remains a spoken one; its third-quarter 10-Q was absent from EDGAR at 11:12 am Eastern on October 22.(12)
The vote is on the filed record. Tesla's charter requires a majority of all outstanding shares, which Musk called "quite a high hurdle."(13)(4) His beneficial ownership, as the proxy measures it, is 19.8 percent of Tesla, and the 423.7 million unearned shares of his 2025 award are voted in proportion to all others.(14) [FILED]
We have written about the law before, on SolarCity and Delaware in July and on Tesla's charter and the Texas code this week, and both states wrote new rules in 2025. Tesla is a Texas corporation. Texas lets a board form a committee for a deal with a controlling shareholder and ask a court, before the deal, to determine whether that committee is independent and disinterested, after notice to the shareholders and a hearing; a governance center at SMU reported in May that no court had yet applied the route.(15) [REPORTED] Delaware's amended statute gives a controller's deal a safe harbor if a committee of disinterested directors or a majority of the votes cast by disinterested stockholders approves it, and requires both when the controller takes the company private; its Supreme Court upheld the amendments in February, answering certified constitutional questions. Delaware's courts had rewarded the same two protections, together, since 2014.(16) [REPORTED] Both states now run on statute: Delaware's has been tested in its Supreme Court, and Texas's awaits its first application. Which route Tesla follows will show up in a filing.
A process can separate the approvals. The roles stay in one person. The same individual is chief executive of both companies, controls SpaceX's vote, beneficially owns nearly a fifth of Tesla, and holds Tesla awards whose terms respond to a change in control: unearned shares under the 2025 award "may become Earned Shares based solely on market capitalization milestones"; "Earned Shares will vest upon the change in control," and the rest are forfeited; and 286.4 million restricted shares from the 2018 award vest early if he is then serving as chief executive or as an executive officer responsible for product development or operations.(14) [FILED] Whether a SpaceX combination would count as a change in control under those awards is for their terms and counsel. Each role carries its own duties, aims and conditions.
Who pays for what
In July we set out Tesla's side of the chip plant: its chief executive had said Optimus depends on it, while Tesla held $43.5 billion of cash and had named Terafab in none of its filings this year.(17)(19) [FILED; REPORTED] The day before, The Cost of Not Beginning priced the same plant from SpaceX's side. On Tesla's call this week:
"We've got to figure out what the relative split is between SpaceX and Tesla in terms of who pays for what at Terafab." (chief executive)
"The first set of equipment for the fab which Tesla is building, we've actually already placed most of the orders." (chief financial officer)(5) [REPORTED]
The chief executive put the bill at "tens of billions" of equipment through early 2028 and "north of $100 billion long term," against the $10.37 billion to $16.8 billion for the first phase in the state and company records we read in October.(5)(18)
Tesla is now paying first, and the split comes later. Its balance sheet carries the spending without naming the project.(1) [FILED; OURS]
- AI computing infrastructure, which the 10-Q labels SI, for super intelligence, rose from $6,816m at December 31 to $10,956m at September 30, and construction in progress from $8,786m to $11,211m.
- Other non-current assets rose by $7,554m. The SpaceX stake, bought in March for $2,002m, is $2,865m of it at September 30;(1) the 10-Q leaves the other $4,689m unitemized and is silent on whether any of it is deposits on fab equipment.
- The 10-Q names Terafab zero times. In its 2026 filings, Tesla first names it in the October 19 proxy materials: "our Terafab initiative."(19)
Any split agreed later is a transaction between affiliates, under Tesla's Related Person Transactions Policy and a new covenant requiring arm's-length terms.(1) [FILED] Meanwhile the dependency widened: Tesla plans 400 megawatts of training compute by year end against SpaceX's 2.5 to 3 gigawatts, Grok rides in the Cybercab, and Tesla's Ashok Elluswamy runs a joint venture with SpaceX called Digital Optimus.(20)(21) [FURNISHED; GUIDED]
The record also runs the other way. Tesla's cash rose $1.9 billion in the quarter to $45.4 billion, free cash flow was positive, and the $30 billion of new facilities are undrawn.(1) [FILED] What the record supports is specific: Tesla is paying for a shared plant before the share is agreed, and its products lean further on its neighbor's compute. Whether that is a cost of not beginning is the reader's call.
The ties, counted again
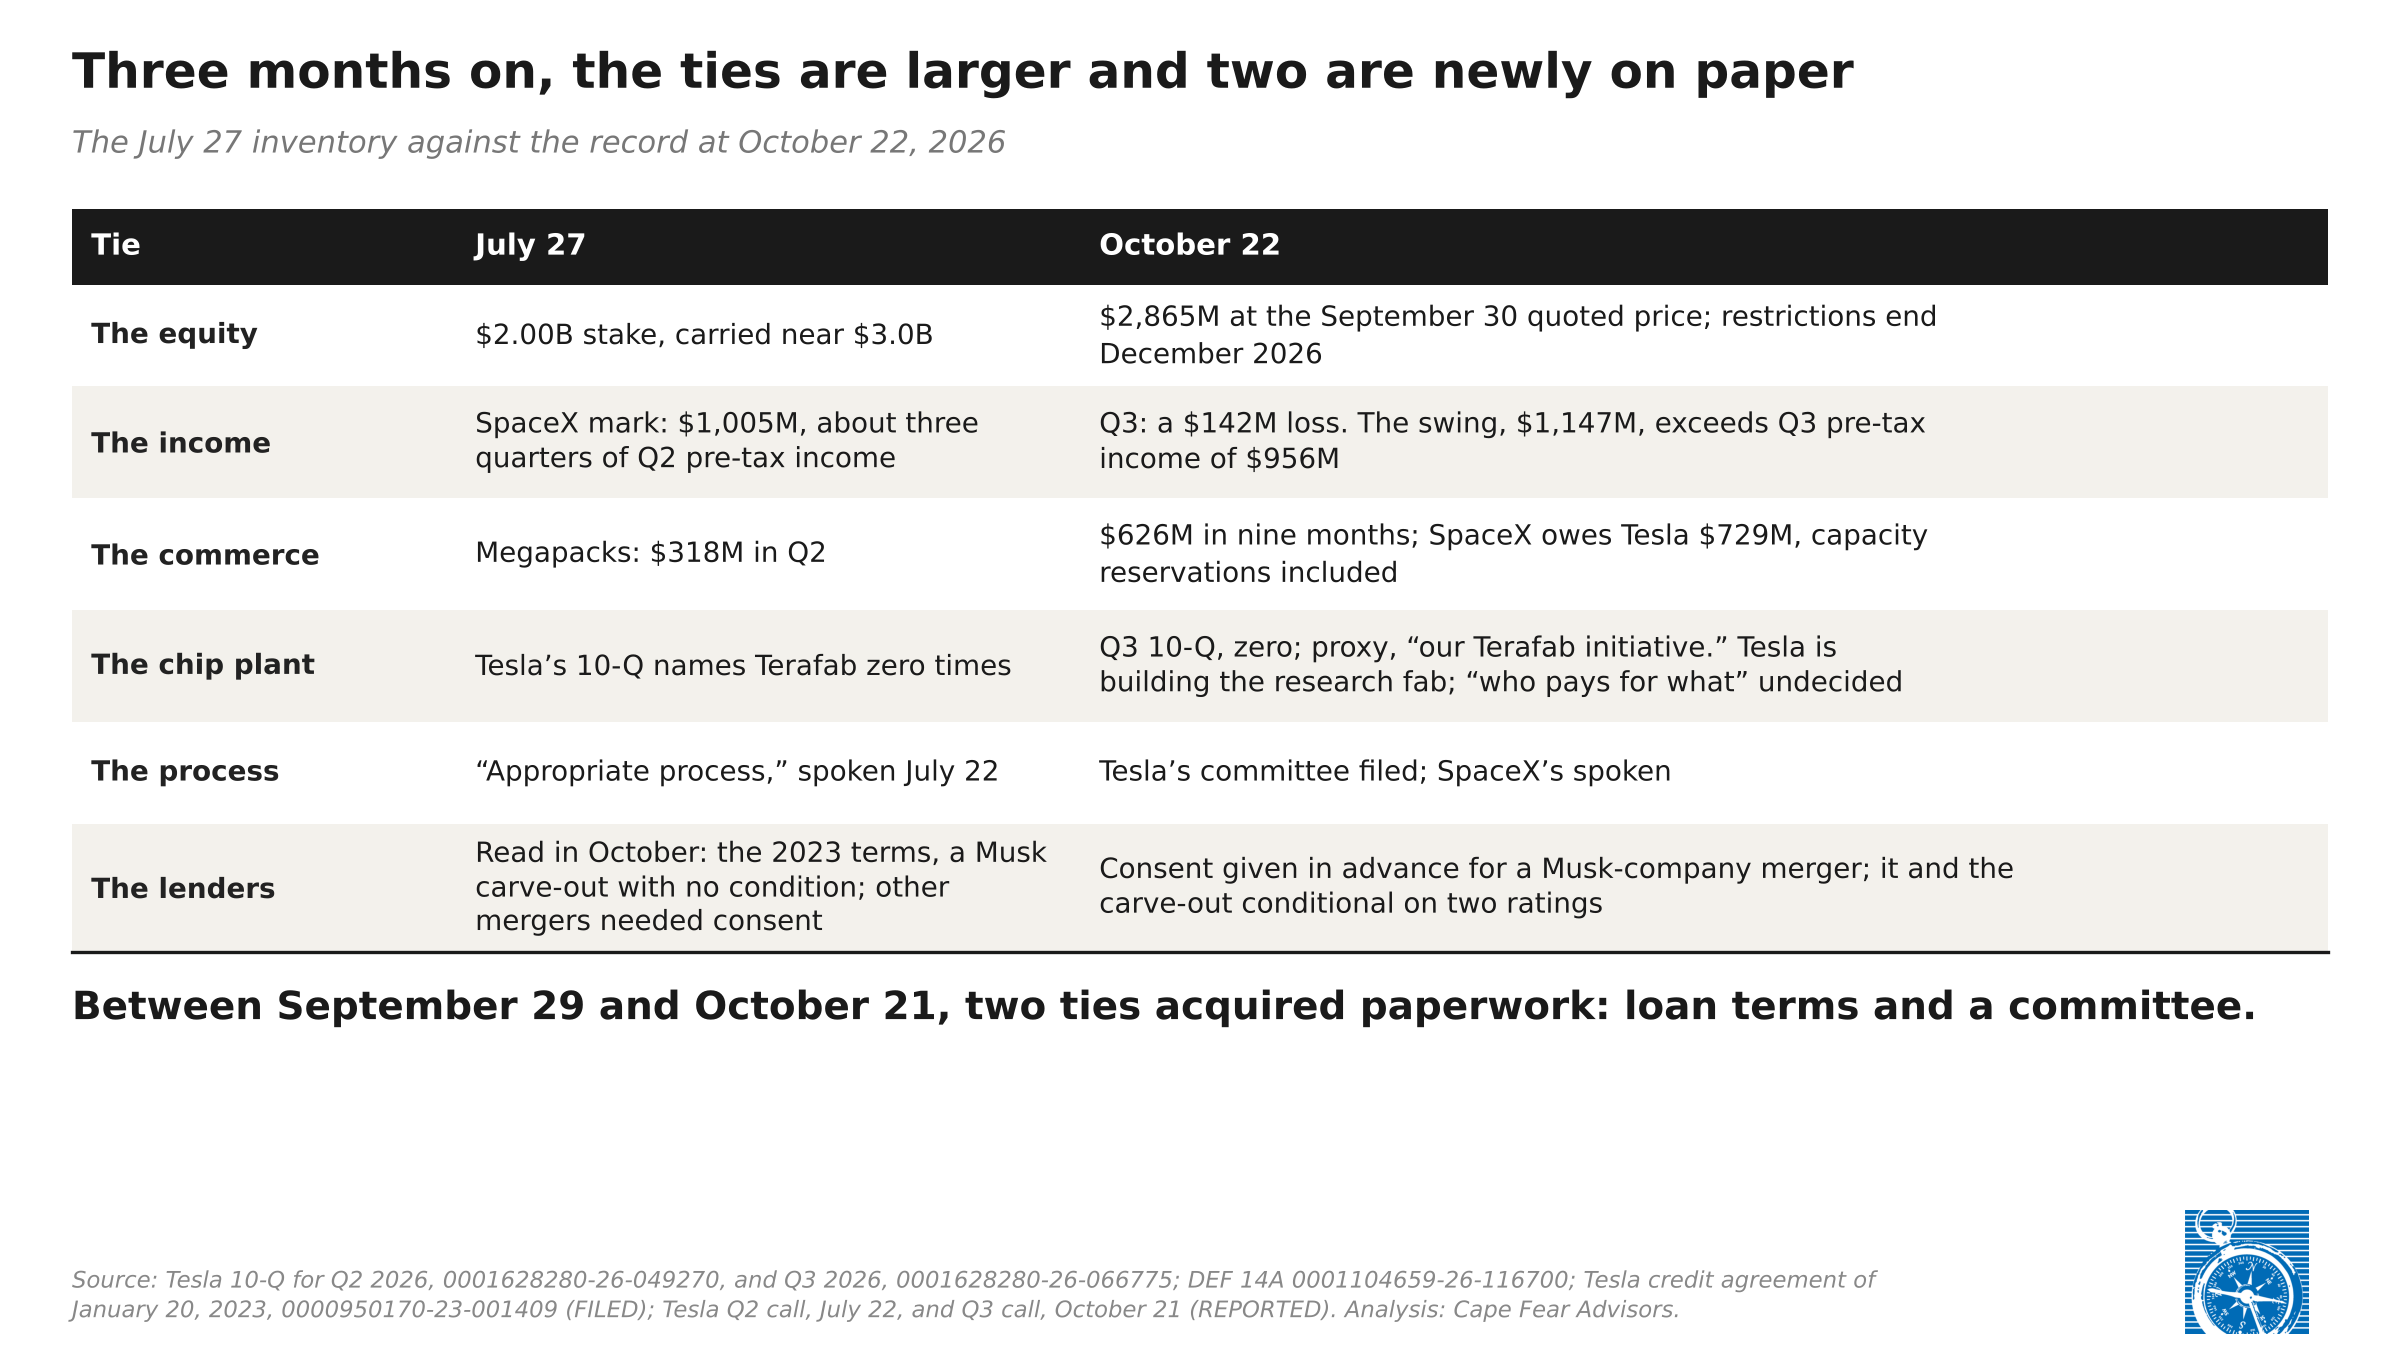
- The mark. Because SpaceX's shares trade, Tesla marks its stake to the market every quarter, up or down, and discloses it plainly. The one cushion, a discount for restricted shares, was released in the third quarter. The mark added $1,005m to Tesla's second quarter and took $142m from its third, a swing larger than the third quarter's $956m of pre-tax income; at the October 21 close the stake sat about $160m above its September 30 value, with two months of the quarter to run.(1)(22) [FILED; OURS] Reported earnings carry the full swing; non-GAAP figures exclude it.
- The commerce. Tesla sold SpaceX $626m of Megapacks in nine months, and at September 30 SpaceX owed Tesla $729m, including capacity reservations. If Tesla's over-10-percent receivables test runs on gross balances, SpaceX alone clears it; the 10-Q leaves the customer unnamed.(1) [FILED; OURS]
- The people. Ira Ehrenpreis sits on both boards.(10) [REPORTED]
What we are waiting for, and when
- By November 16: SpaceX's third-quarter 10-Q, due on a 45-day deadline. Whether it files its own committee paragraph, what its related-party note says about Tesla, and whether any credit agreement signed since June carries terms like Tesla's.(12) [OURS]
- Any day: a rating action on Tesla or SpaceX. The lenders made the rating the price of keeping $30 billion of commitments through a combination.
- When terms exist: a Form 8-K under Item 1.01 or 8.01, or a Rule 425 filing, and with it the route: a deal put to the shareholders other than Musk, or a Texas court petition on the committee's independence, which the statute requires Tesla to make known to its shareholders other than the controller, by a current report if it chooses, with a preliminary hearing on their counsel at least 10 days later.(15)
- December 2026: the end of the listing restrictions on Tesla's SpaceX shares, and the fourth-quarter mark.
- The first half of 2027: commissioning at the Austin research fab, the one "Tesla is building," and with it the first sign of who pays for what.(5)
Free to read, no paywall. Corrections run in daylight, dated, in a comment or in the following piece.
Standing Disclosure
Cape Fear Advisors' principal holds a small long position in Tesla call options, held since earlier in 2026, and no other position in the securities discussed, other than any held through broad index or pooled funds over which he exercises no control. Anthropic, a SpaceX cloud customer, develops Claude, which is used in preparing this research. The same standard of reading is applied to every filer named.
Notes
(1) Tesla, Inc., Form 10-Q for the quarter ended September 30, 2026, accession 0001628280-26-066775, accepted by EDGAR at 8:12 pm Eastern on October 21 with a filing date of October 22: Part II, Item 5 (the Special Committee); Note 3 (the acquisition of a Super Intelligence ("SI") hardware company, which defines the label); Notes 1 and 2 (SpaceX equity investment, Level 1, release of the discount for lack of marketability, restrictions expiring December 2026); Note 5 (property, plant and equipment); Note 13 (related party transactions, including the $2.00 billion invested in SpaceX common stock "in March 2026," formerly a preferred share investment in xAI; the 10-Q gives no day); concentration of credit risk; balance sheet and cash flows. Exhibits 10.1, 10.2 and 10.3, each dated September 29, 2026: definitions of "Permitted Holder," "Specified Merger," "Specified Transaction," "Specified Holding Company," "Qualified Permitted Holder," "Qualified Holding Company," "Ratings Requirement," "Ratings Test Period," "Ratings Trigger Date" and "Change in Control"; Section 6.03 (Fundamental Changes); Section 6.06 (Transactions with Affiliates); Section 7.01(m), and the paragraph closing Section 7.01, under which the Required Lenders may on an Event of Default terminate the Commitments and declare any Loans due. On a ratings failure, the transaction becomes a Change in Control on the later of its completion and 60 days after the Ratings Trigger Date. FILED.
(2) Tesla, Inc., Form 8-K, September 29, 2026, accession 0001628280-26-063820, Items 1.01, 1.02 and 2.03: a $20 billion delayed draw term loan, an $8 billion five-year revolver and a $2 billion 364-day revolver; general corporate purposes; "Tesla does not currently plan to draw on the facilities in 2026." FILED.
(3) Moody's Baa3 for Tesla and Baa1 for SpaceX, and S&P BBB for Tesla, as reported by Electric Vehicles, June 19, 2026. Fitch's first-time BBB for Tesla, Stable: Fitch's rating action text as reproduced by EVSHIFT on September 22, 2026 (relevant committee August 26), and Electric Vehicles, September 23, 2026, which dates the action "on Monday," September 21. Either date precedes the September 29 agreements. Not verified at the agencies. REPORTED.
(4) SpaceX third-quarter call, October 20, 2026, question from Deutsche Bank. Wording checked across the Motley Fool, Benzinga and Investing.com transcripts; quoted passages appear in at least two. REPORTED.
(5) Tesla third-quarter call, October 21, 2026. Wording checked across the Benzinga and Investing.com transcripts, with Shacknews live notes for substance. REPORTED.
(6) Tesla, Inc., Credit Agreement dated January 20, 2023, Exhibit 10.59 to the Form 10-K for 2022, accession 0000950170-23-001409: "Change in Control" and "Permitted Holder"; Section 6.03 (Fundamental Changes), which permits a Restricted Subsidiary to merge into the Borrower and contains no provision for any other Person to do so; Article VII (Events of Default); Section 9.02(b), under which any waiver, amendment or modification requires a written agreement with the Required Lenders. Ratings appear only in the Pricing Grid; no rating condition and no merger condition were found in the agreement as read. FILED.
(7) Elon Musk, Form 3 for Space Exploration Technologies Corp., June 11, 2026, accession 0001628280-26-042628: holdings "By Elon Musk Revocable Trust," "By Musk 2017 Sprinkling Trust" and "By Mission Trust." FILED.
(8) EDGAR full-text search, which covers filings from 2001, run at 11:12 am Eastern, October 22, 2026: "Qualified Permitted Holder" returns three documents, Exhibits 10.1, 10.2 and 10.3 to accession 0001628280-26-066775. OURS.
(9) Space Exploration Technologies Corp.: Amended and Restated Credit Agreement, May 19, 2026, $5.0 billion, Exhibit 10.10 to the Form S-1/A, accession 0001628280-26-039276; Bridge Loan Credit Agreement, March 2, 2026, Exhibit 10.9 to the Form S-1, accession 0001628280-26-036936; Indenture, June 26, 2026, Exhibit 4.1 to the Form 8-K, accession 0001628280-26-045763, governing five series of notes totaling $25.0 billion. FILED.
(10) The Wall Street Journal, Becky Peterson and Corrie Driebusch, "SpaceX and Tesla Are Joined at the Hip. A Merger Would Make It Formal," October 21, 2026: an all-stock structure, as described by investors and analysts; Ehrenpreis's seats on both boards. REPORTED.
(11) The SpaceX revolver's "Change of Control," clause (c), refers to a change of control under any Indebtedness whose aggregate principal amount, "including undrawn committed or available amounts," exceeds the $500 million Threshold Amount; its Events of Default, clause (e), Cross-Default, reaches the Borrower "or any Subsidiary" and measures the same way. The definition of "Indebtedness" itself refers to liabilities appearing on the balance sheet. The clause's measuring parenthetical and the definition are both quoted as written; how they interact is for counsel. Tesla's Form 10-K description of securities, Exhibit 4.17, accession 0001628280-26-003952, states that Tesla is subject to Section 21.606 of the Texas Business Organizations Code. FILED. No reading of either is offered.
(12) EDGAR submissions and full-text search for CIK 1181412, 11:12 am Eastern, October 22, 2026: no 10-Q for the quarter ended September 30; SpaceX's latest filing is its October 20 current report, and it has filed nothing under Rule 425. The 45-day deadline assumes non-accelerated filer status in the first year after listing; November 14 is a Saturday. OURS.
(13) Tesla, Inc., Certificate of Formation, Exhibit 3.1 to the Form 10-Q for the quarter ended June 30, 2024, accession 0001628280-24-032662. The Form 10-K for 2025 (0001628280-26-003952) incorporates the same certificate, and Tesla's only Item 5.03 report since, May 16, 2025 (0001104659-25-050072), amended its bylaws. FILED.
(14) Tesla, Inc., Definitive Proxy Statement, October 19, 2026, accession 0001104659-26-116700: beneficial ownership at September 30, 2026; the voting of unearned 2025 award shares in proportion to all other shares present; the 2025 CEO Performance Award's change-in-control terms ("Unearned Shares may become Earned Shares based solely on market capitalization milestones... Earned Shares will vest upon the change in control, and Unearned Shares will be automatically forfeited"); the 286,428,773 restricted shares from the June 16, 2026 exercise of the 2018 award, which "vest on an accelerated basis if Mr. Musk is serving either as our CEO or as an executive officer responsible for product development or operations upon a change in control." The special committees the proxy describes concern compensation; it describes none on SpaceX. FILED.
(15) Texas Senate Bill 29 (2025), Texas Business Organizations Code §21.416(g) and §21.4161. Section 21.4161, read at the Texas Legislature's statutes site on October 22, 2026: the petition is filed in the business court; the corporation designates counsel for the shareholders other than the controller and gives them notice, which a listed corporation may give by a current report filed with the SEC; and the court holds a preliminary hearing "not earlier than the 10th day after" notice. FILED. The decisions are as summarized by the SMU Corporate Governance Initiative, "Texas SB 29: Statutory Reform," May 27, 2026, which reports no court decision applying them. REPORTED. A web search on October 22, 2026 found no reported petition or decision under §21.4161; the SB 29 ruling it did find, a federal court in March 2026, concerned the ownership threshold for derivative suits. OURS.
(16) Delaware Senate Bill 21 (2025), amending 8 Del. C. §144 (safe harbors for controlling stockholder transactions: approval by a committee of disinterested directors or by a majority of the votes cast by disinterested stockholders, and both for a going-private transaction); upheld in Rutledge v. Clearway Energy Group LLC (Del. Feb. 27, 2026), which answered constitutional questions certified to the Supreme Court and records no transaction clearing the safe harbor, as reported by WilmerHale, February 27, 2026, and other firms. Kahn v. M&F Worldwide Corp., 88 A.3d 635 (Del. 2014). Described, not applied. REPORTED.
(17) Cape Fear Advisors, "SpaceX and Tesla, Adding It Up: The State of the Merger," July 27, 2026, and "SpaceX, Adding It Up: The Cost of Not Beginning," July 26, 2026. Cash of $43,524m at June 30, 2026 (Tesla second-quarter 10-Q). FILED.
(18) Cape Fear Advisors, "SpaceX, Adding It Up: Terafab Is Stateless," October 3, 2026: $10.37 billion in the Texas JETI applications (filed locally) and $16.8 billion on SpaceX's web page (REPORTED), for Phase 1.
(19) Tesla, Inc., Definitive Proxy Statement (0001104659-26-116700), Annual Report to Shareholders (0001104659-26-116718) and Definitive Additional Materials (0001104659-26-116948), all October 19, 2026. EDGAR full-text search of Tesla's 2026 filings for "Terafab," run at 11:12 am Eastern, October 22, 2026, returns these three and no others. Tesla has filed nothing since the 10-Q. FILED; OURS.
(20) Tesla Third Quarter 2026 Update, Exhibit 99.1 to the Form 8-K, October 21, 2026, accession 0001628280-26-066738: 400 MW of SI training compute planned by year end; Grok in Cybercab. SpaceX third-quarter release, October 20, 2026, accession 0001628280-26-066482, and call: 2.5 to 3 GW by year end. FURNISHED; GUIDED.
(21) Digital Optimus: Tesla First Quarter 2026 Update, Exhibit 99.1 to the Form 8-K, April 22, 2026, accession 0001628280-26-026551. FURNISHED.
(22) Our arithmetic. $2,865m at the September 30 close of $150.86 implies about 19.0m shares. At the June 30 close of $170.86 those shares were valued at about $3,245m against about $3,007m carried ($2,002m paid plus the $1,005m second-quarter gain), a discount of about $238m, which explains a mark down 4.7 percent against a stock down 11.7 percent. 19.0m shares times the $8.45 move to the October 21 close of $159.31 is about $160m. Closing prices from stockanalysis.com (REPORTED). OURS.
Analysis: Cape Fear Advisors.
This piece also appears on Substack. Cape Fear Advisors is an independent advisory firm based in Portsmouth, NH.
Contact Cape Fear Advisors