
Anthropic's amended prospectus, filed November 10, names the companies that supply it, invest in it and host its capacity. Most of those companies file with the SEC too. Read side by side, the two records describe eighteen relationships, and both records name the tie in four of them.
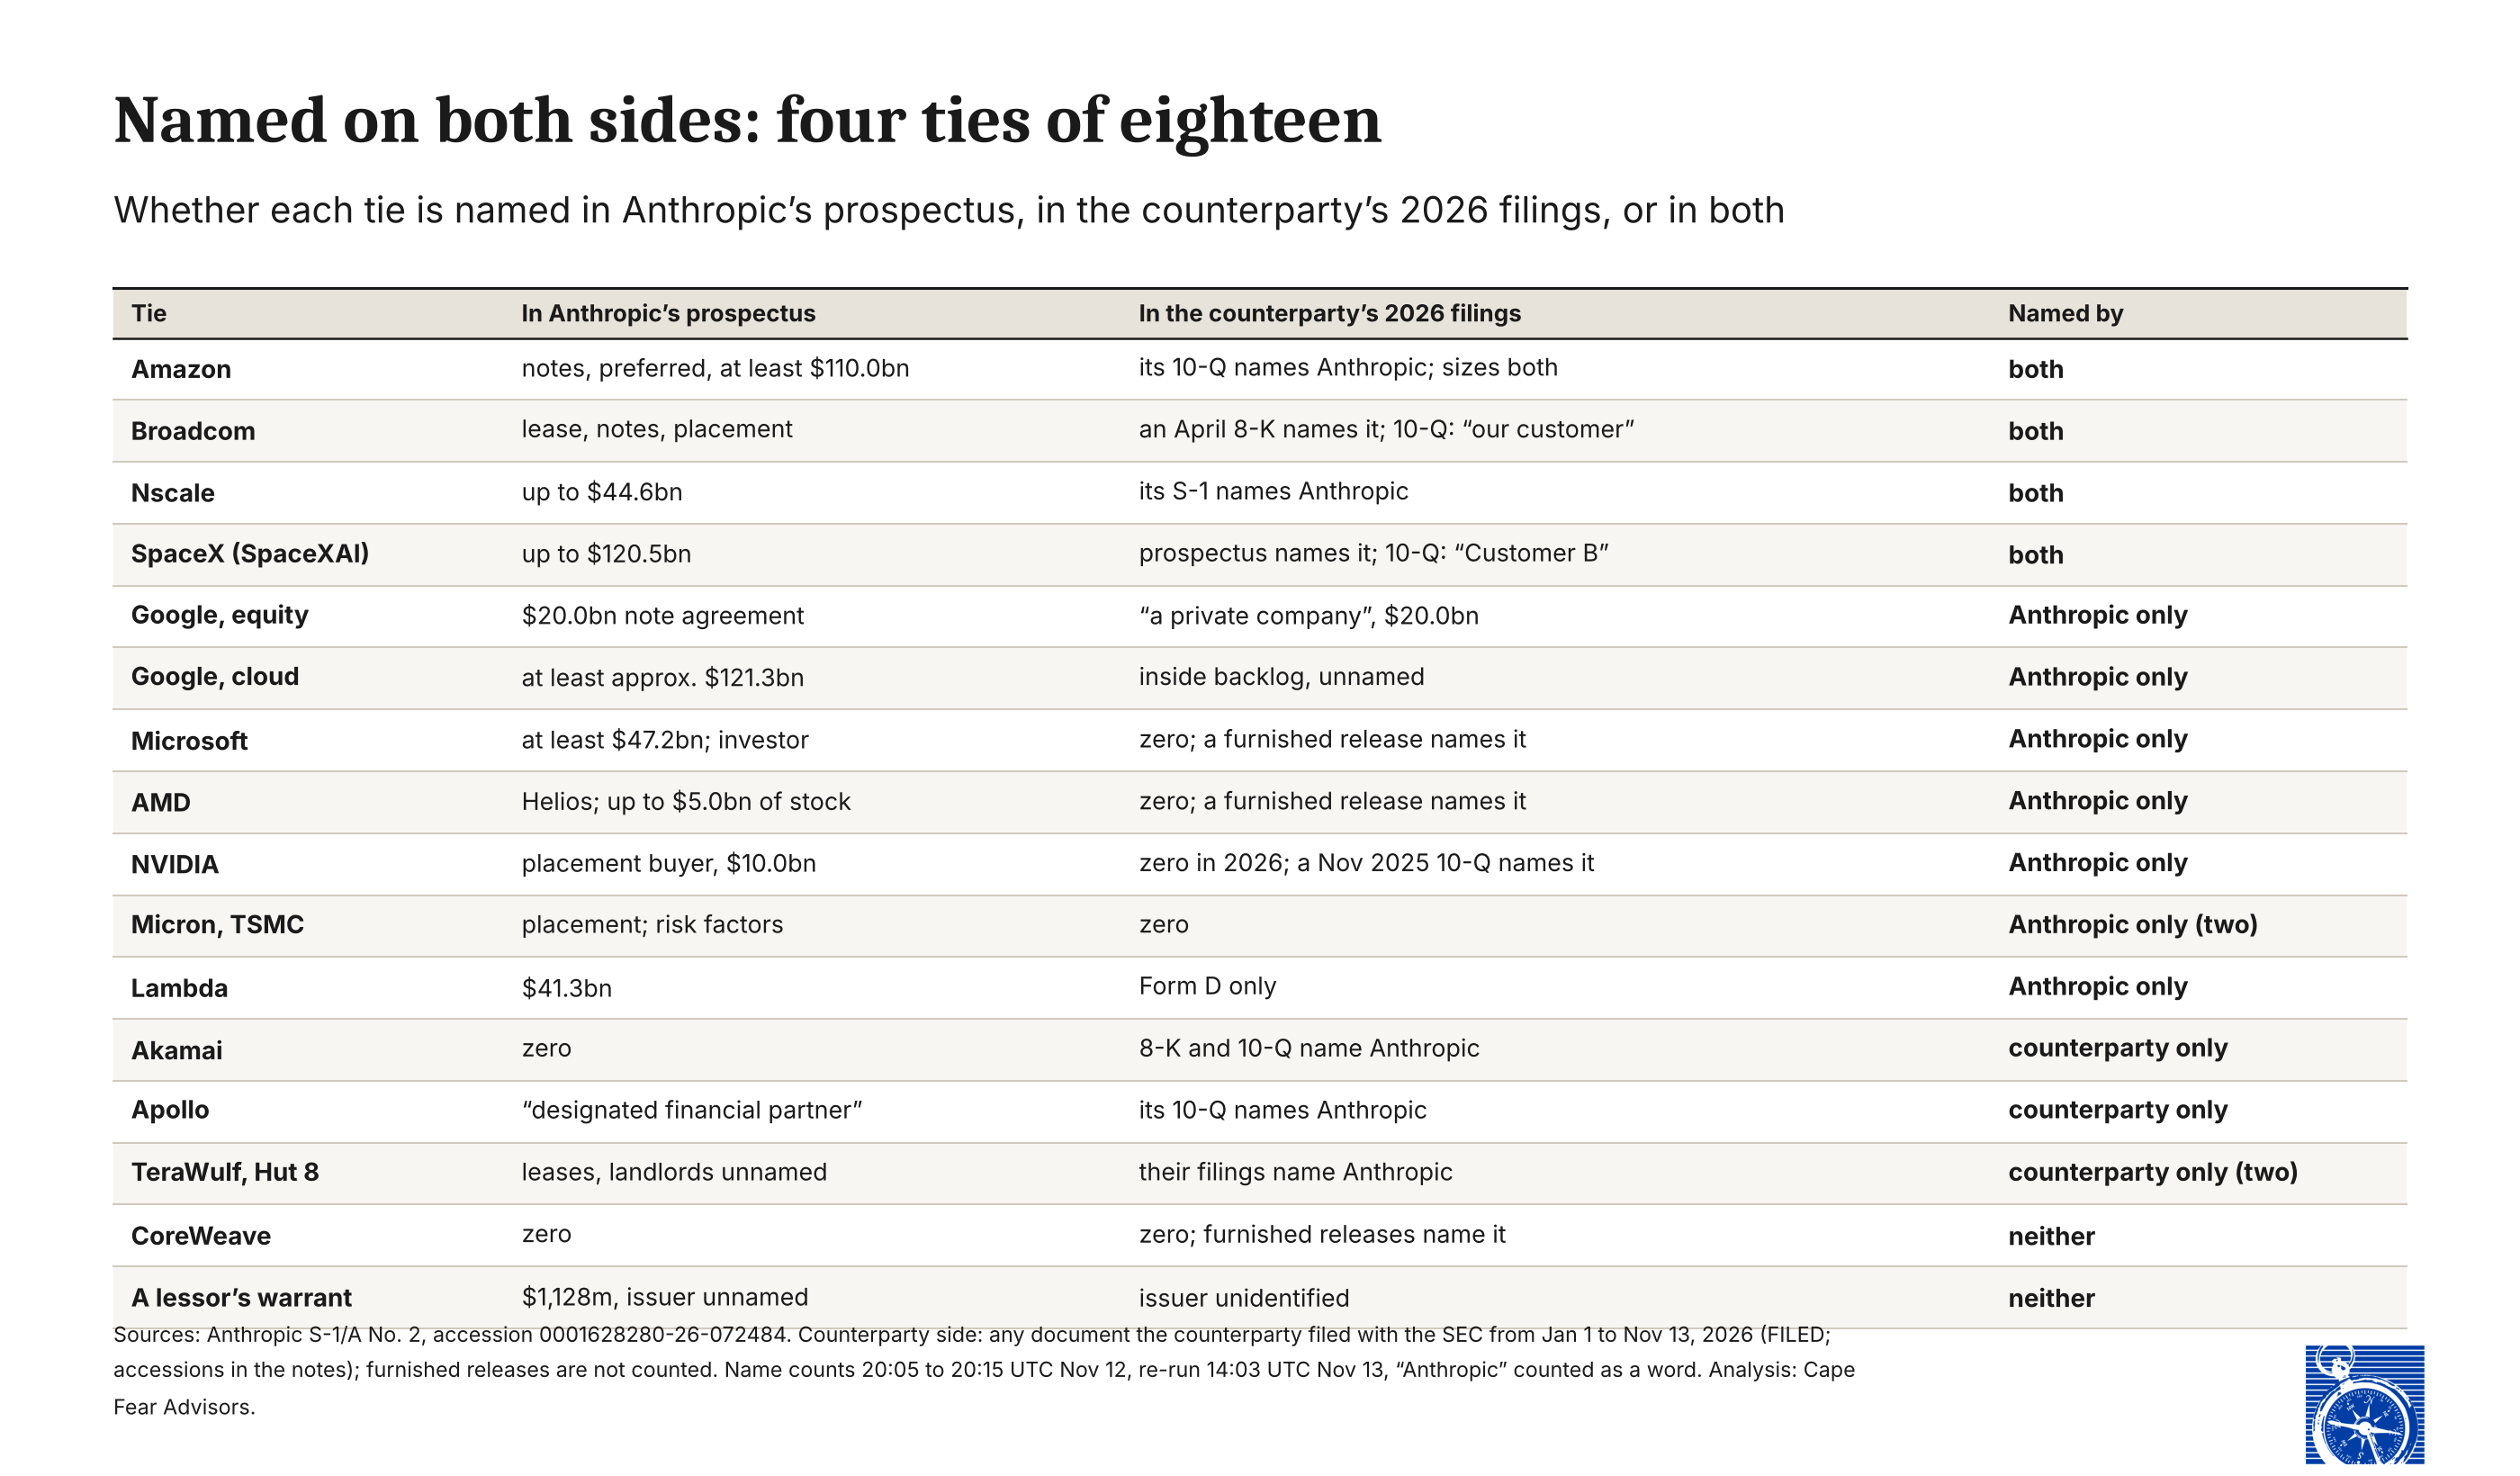
A tie here is one relationship between Anthropic and one counterparty, so Google's equity and its cloud contract count as two. The counterparty's side is read across everything it filed with the SEC in 2026. SpaceX is the filer; SpaceXAI is the subsidiary Anthropic names. Of eighteen ties, four are named on both sides: Amazon, Broadcom, Nscale and SpaceX. Eight are named only in Anthropic's prospectus, NVIDIA among them; its one naming is a 10-Q from November 2025. Four are named only by the counterparty; Akamai is one, named in its own 8-K and 10-Q and nowhere in Anthropic's prospectus, though Anthropic has committed about $11.6 billion to it. Two are named by neither. (1)
The four named on both sides narrow further in the reports that recur. Broadcom names Anthropic in an April 8-K, and its 10-Q refers to "our customer." SpaceX names Anthropic in its prospectus and letters it "Customer B" in its 10-Q. Nscale has yet to file a periodic report. Of the four, Amazon alone names Anthropic in its latest periodic report. (2)
Where naming begins
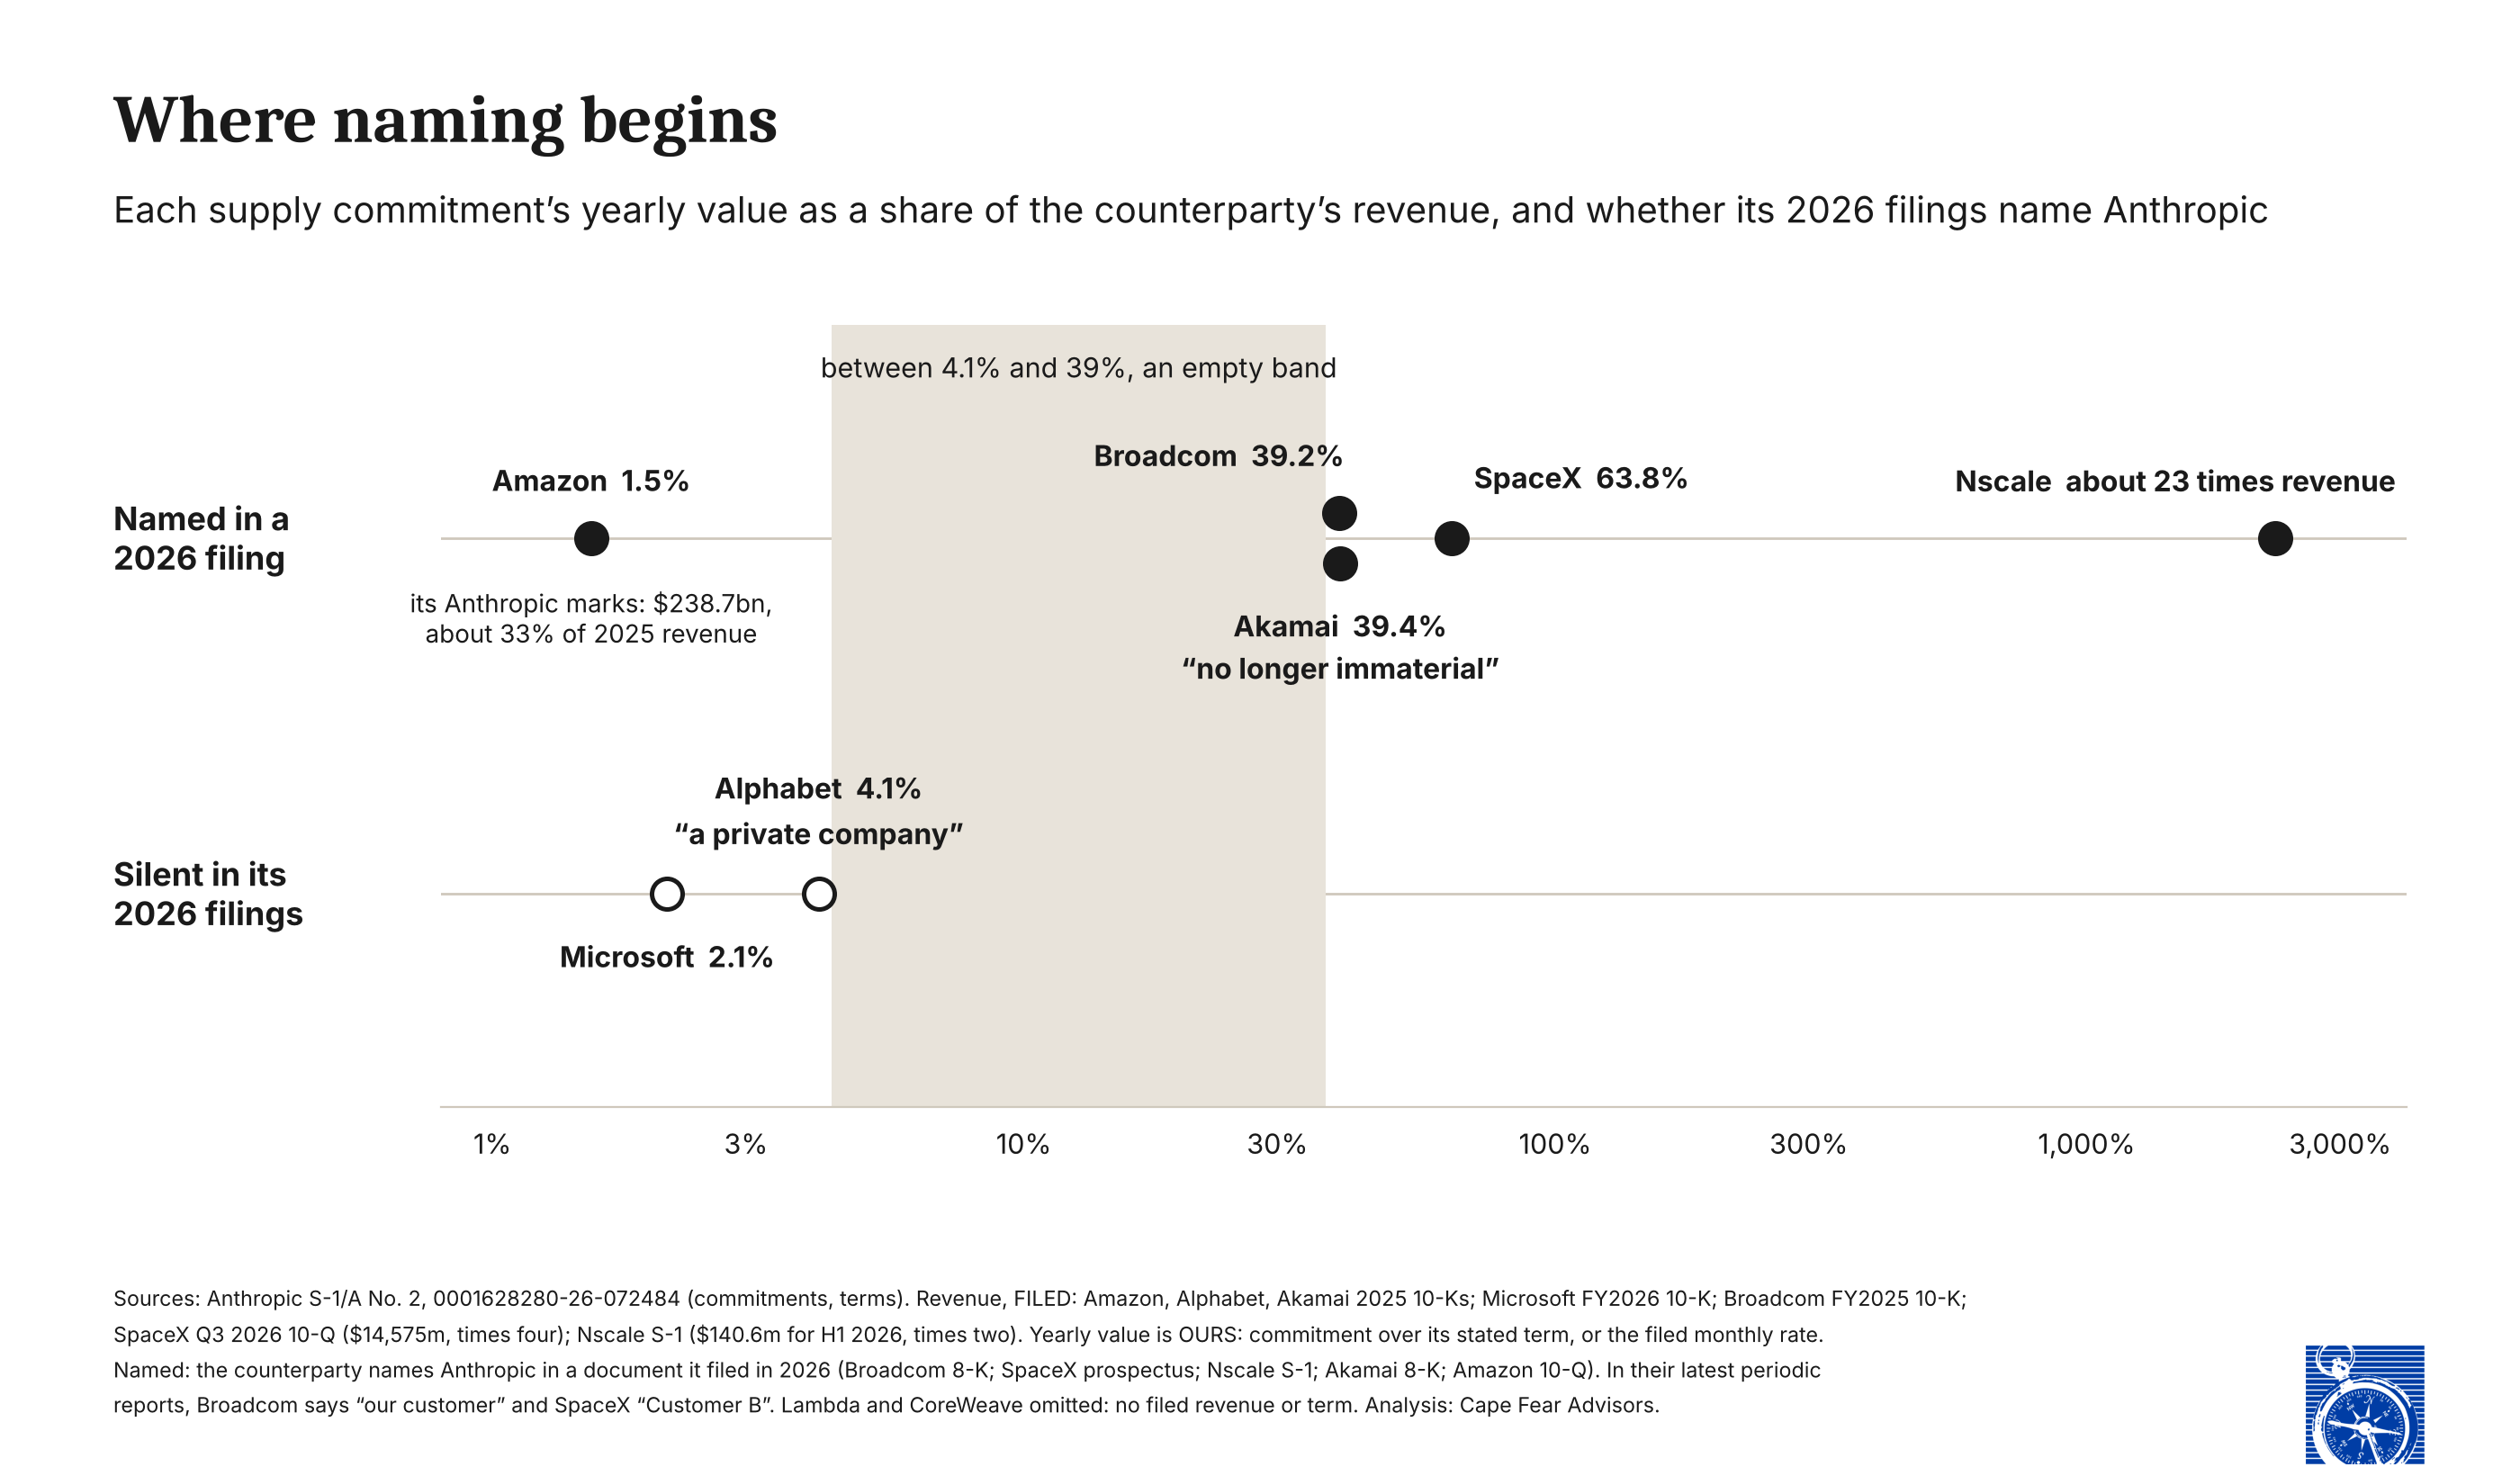
Naming tracks how large the supply tie is for the company doing the naming. Set each supply commitment's yearly value against the counterparty's own revenue:
- Nscale, SpaceX, Akamai and Broadcom sit at 39 percent or more, Nscale at about 23 times its revenue, and each names Anthropic in a 2026 filing.
- Alphabet and Microsoft sit at 4.1 and 2.1 percent, and name Anthropic nowhere in their 2026 filings. Alphabet sizes the $20.0 billion commitment and calls the counterparty "a private company."
- Among these seven, the band between 4.1 and 39 percent is empty.
- Amazon sits at 1.5 percent and names Anthropic, the one exception on this measure. (3)
The two edges of the empty band carry the point. Anthropic's $11.6 billion with Akamai, over seven years, runs at about $1.66 billion a year, 39 percent of Akamai's revenue, and Akamai's 8-K calls the agreement "no longer immaterial in amount or significance to the Company." The "at least approximately $121.3 billion" with Google runs at about $16.5 billion a year, about 4 percent of Alphabet's revenue, and Alphabet's filings describe the counterparty as "a private company."
The rule holds in the documents an event forces: an 8-K, a prospectus, an S-1. In the reports that recur, size does not sort the four with a 10-Q on file. Amazon at 1.5 percent and Akamai at 39 percent name Anthropic in their 10-Qs; Broadcom at 39 percent and SpaceX at 63 percent letter it, "our customer" and "Customer B."
Investment size is untested on this record. Amazon's marks on Anthropic equal about 33 percent of its 2025 revenue, and Amazon names it. Alphabet's whole private-company book, every position in it, equals about 31 percent of its revenue, so its Anthropic position can be no larger; its size is unstated, and Alphabet's gains come "largely from a private company" it leaves unnamed. On this record, supply size tracks naming; investment size awaits a filer that states both the position and the name. (4)
Anthropic's own silences follow a rule. Its principal holders and related persons are defined by voting securities, and the investor-suppliers hold nonvoting Class N under ownership caps of 12 percent for Amazon and 14.99 percent for Google. The largest relationships in the document sit outside the sections built to show related parties. (5)
The two "neither" rows are of different kinds. CoreWeave's tie appears only in CoreWeave's furnished releases and an investor deck, and both sides' filings are silent on it. The lessor's warrant carries a filed value, $1,128 million, with the issuer withheld. Either absence leaves the size of the tie open. What a filer was required to disclose is a judgment made inside the company, out of view, so the record states what was filed and stops there.
The same tie, two prices
Amazon, the one investor-supplier that names Anthropic in its latest periodic report, carries its position at $238.7 billion: $146.2 billion of convertible notes and $92.5 billion of nonvoting preferred. That is more than twice the at least $110.0 billion Anthropic has committed to spend with Amazon. (6)
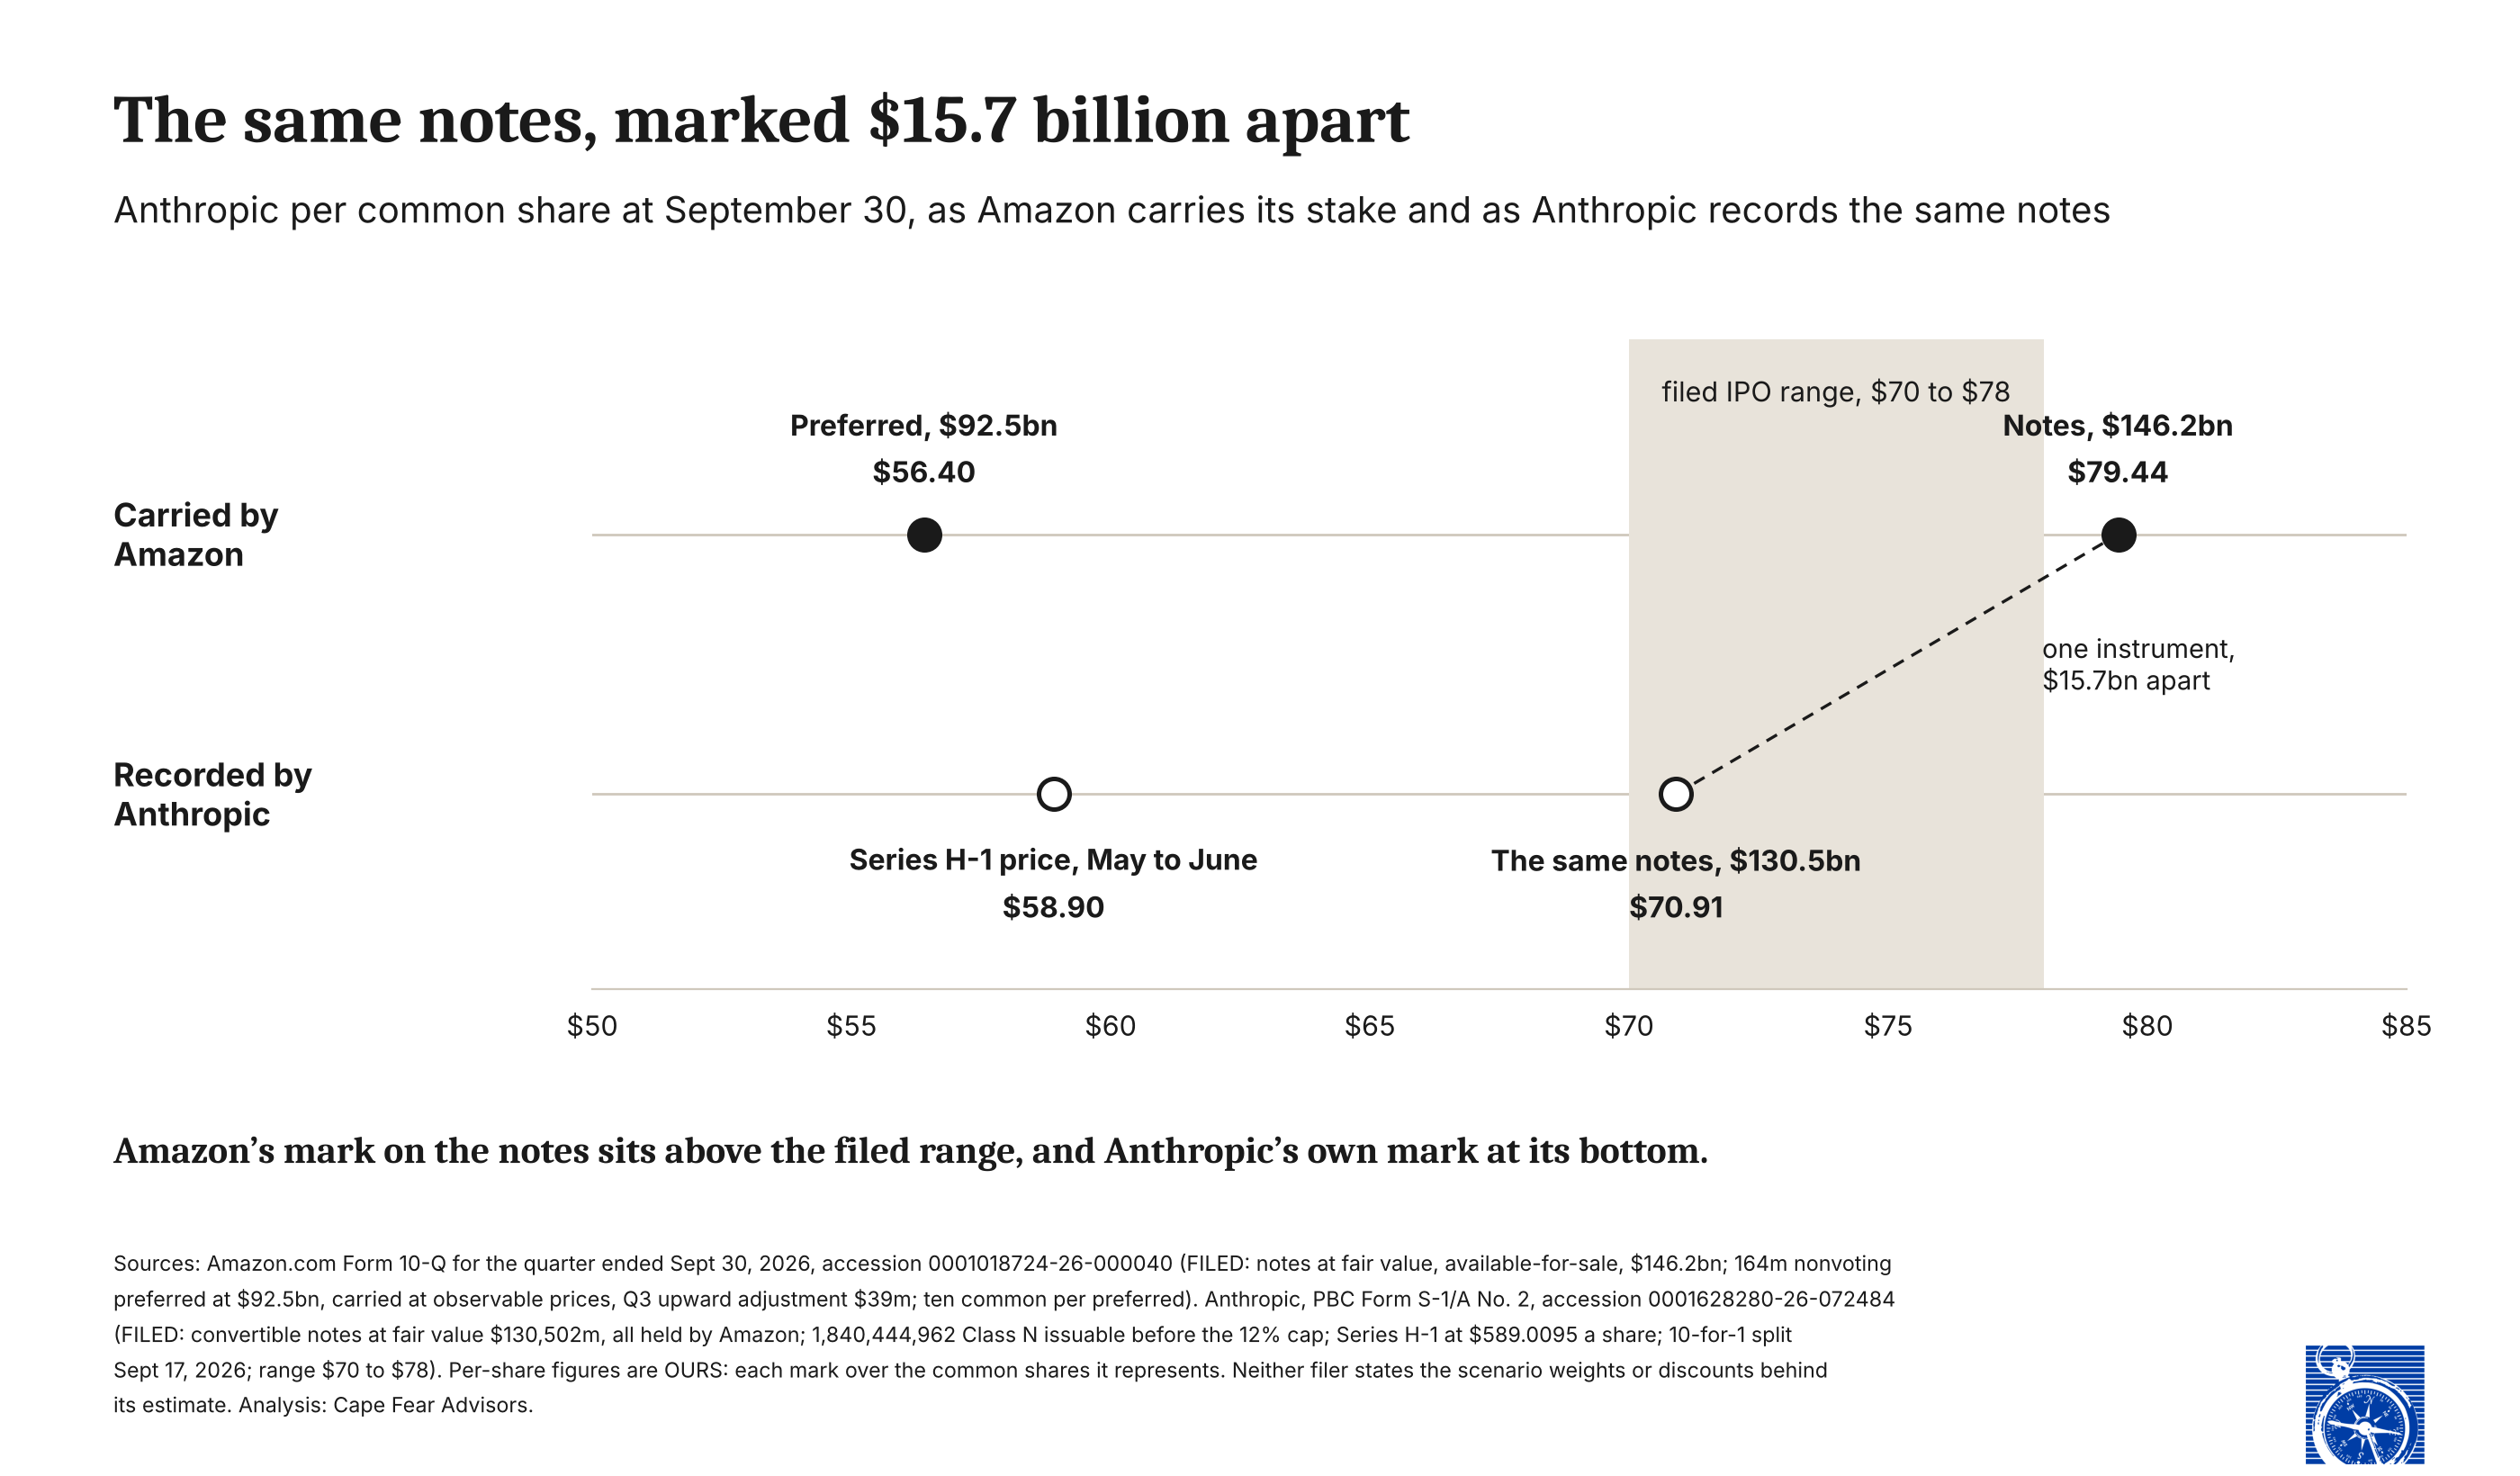
Per common share, Amazon's two marks sit about 40 percent apart: about $79.44 on the notes and about $56.40 on the preferred. The gap is one of method. Amazon carries the notes at fair value each quarter, with inputs that include "anticipated securities offerings." It carries the preferred at the last observable price, adjusted when a new one appears, and its third-quarter adjustment was $39 million. The last observable price was Anthropic's Series H-1 round of May and June, at $589.0095 a share, or $58.90 after September's ten-for-one split. (7)
The sharper pair is the notes themselves, as recorded by each party. Every Anthropic note outstanding is Amazon's, and Anthropic carries them as a liability at fair value: $130.5 billion at September 30, about $70.91 a share. Amazon carries the same notes at $146.2 billion. Holder and issuer value one instrument, on one date, $15.7 billion apart; Anthropic's mark sits just inside the bottom of the filed range of $70 to $78, and Amazon's above its top. Holder and issuer measure from different positions, and a liability's fair value reflects the issuer's own credit, so some gap is expected; the size of this one is unexplained. Anthropic books its side of the same revaluation as a charge: $94.3 billion in the nine months to September 30, from increases in the notes' fair value "resulting from increases in our enterprise valuation." Neither filer states the scenario weights or discounts behind its estimate. (8)
Both directions
Supplier money into Anthropic is the familiar direction. The record also runs the other way: Anthropic holds equity rights in two of the companies building for it, and the rights grow with the commitment.
Akamai, under the project plans that carry Anthropic's $11.6 billion commitment, issued Anthropic a warrant over 7,741,020 Akamai shares as converted, at $111.33, exercisable for seven years. Forty percent vests on Anthropic's first payment under Project Plan 3, and 20 percent more for each further $3.0 billion committed; by our arithmetic, vesting completes at $20.6 billion. The full warrant covers about 5.3 percent of Akamai's outstanding shares. (9)
Akamai is funding the buildout in the bond market. On November 12 it closed $2.5 billion of convertible notes in two tranches, each at 1 percent, in part to "fund the capital expenditure requirements of its Cloud Infrastructure Services (CIS) business." The 2028 notes convert at about $112.41, $1.08 above Anthropic's strike. Akamai's 2028 bondholders and Anthropic hold rights to Akamai shares at nearly the same price, Anthropic's vesting with its commitment, 40 and 38 percent above the November 9 close of $80.29. (10)
A second lessor gave Anthropic warrant rights over a privately held company's common shares, "as consideration under an agreement entered into but not yet commenced." Their fair value rose from $345 million at the end of 2025 to $1,128 million at September 30, before the lease has begun. On commencement the rights are "recognized as lease incentives," against the cost of the lease. The issuer is unnamed. (11)
The placement ties a supplier's return to Anthropic's shares. These warrants tie part of Anthropic's return to its suppliers' shares, and in both cases the equity is part of the price of the sale.
The roads back
The ties exist because a supplier's money can come back five ways, and most of these companies hold more than one.
The stake. The shares themselves, marked at the IPO price and after it.
The sale. Anthropic's spending with the investor. Anthropic has committed to spend "at least approximately $121.3 billion" with Google through July 2033, "regardless of actual usage," with further TPU compute estimated at $125.0 billion to $150.0 billion outside the obligations table; "at least $47.2 billion and up to $49.2 billion" with Microsoft through June 2033; and "at least $110.0 billion" with Amazon through April 2036. Broadcom's lease rent runs to about $125.2 billion. (12)
The chain. Spending that reaches the investor one step out. NVIDIA holds no supply contract on Anthropic's record. SpaceXAI, Nscale and Lambda each sell Anthropic "compute powered by NVIDIA GPUs," up to about $206.4 billion between them, and none of the three is in the placement. On one of the three, the loop closes on its own record: Nscale's S-1 shows NVIDIA guaranteeing up to $860.3 million of an Nscale lease in Ward County, Texas, in exchange for warrants. Our August construction, the required share, asks how much of a customer's program has to come back to the supplier for a placement to return its own cash. (13)
The channel. Anthropic's own sales, running back through the investor. Claude is sold through the cloud marketplaces of Amazon, Google and Microsoft, which "bill end customers, collect payments on our behalf, and remit such amounts to us, net of applicable platform and other fees." Those sales were about 44 percent of Anthropic's revenue in the nine months to September 30, and 52 percent of its receivables. Anthropic "is the principal and recognizes revenue on a gross basis"; the platforms' share sits in its expenses. Three of the companies that sell Anthropic its compute also sell its product, and keep a fee on each sale. (14)
The entanglement. Positions beyond the other four roads. Broadcom will hold up to $42.0 billion of Anthropic notes "to finance obligations under the 2026 Lease Arrangement," rent owed to Broadcom itself. Google offers further TPUs by "direct purchase from Google with five-year financing." Amazon's notes can settle "by set-off against certain amounts Amazon owes us under our commercial agreements." (15)
Committed first, priced later
Seven companies have agreed to buy $26.0 billion of nonvoting Class N stock at the IPO price, "severally and not jointly": Google and NVIDIA $10.0 billion each, AMD $2.5 billion, Broadcom, Microsoft and Micron $1.0 billion each, and TSMC Partners $0.5 billion. Of that, $22.5 billion, 86 percent, was promised months ago, by Google, AMD and NVIDIA; the link between NVIDIA's 2025 agreement and this purchase is ours. At the $74 midpoint the IPO buyers put in about $59.3 billion, about 94 percent of the new money to Anthropic decided at the IPO. (16)
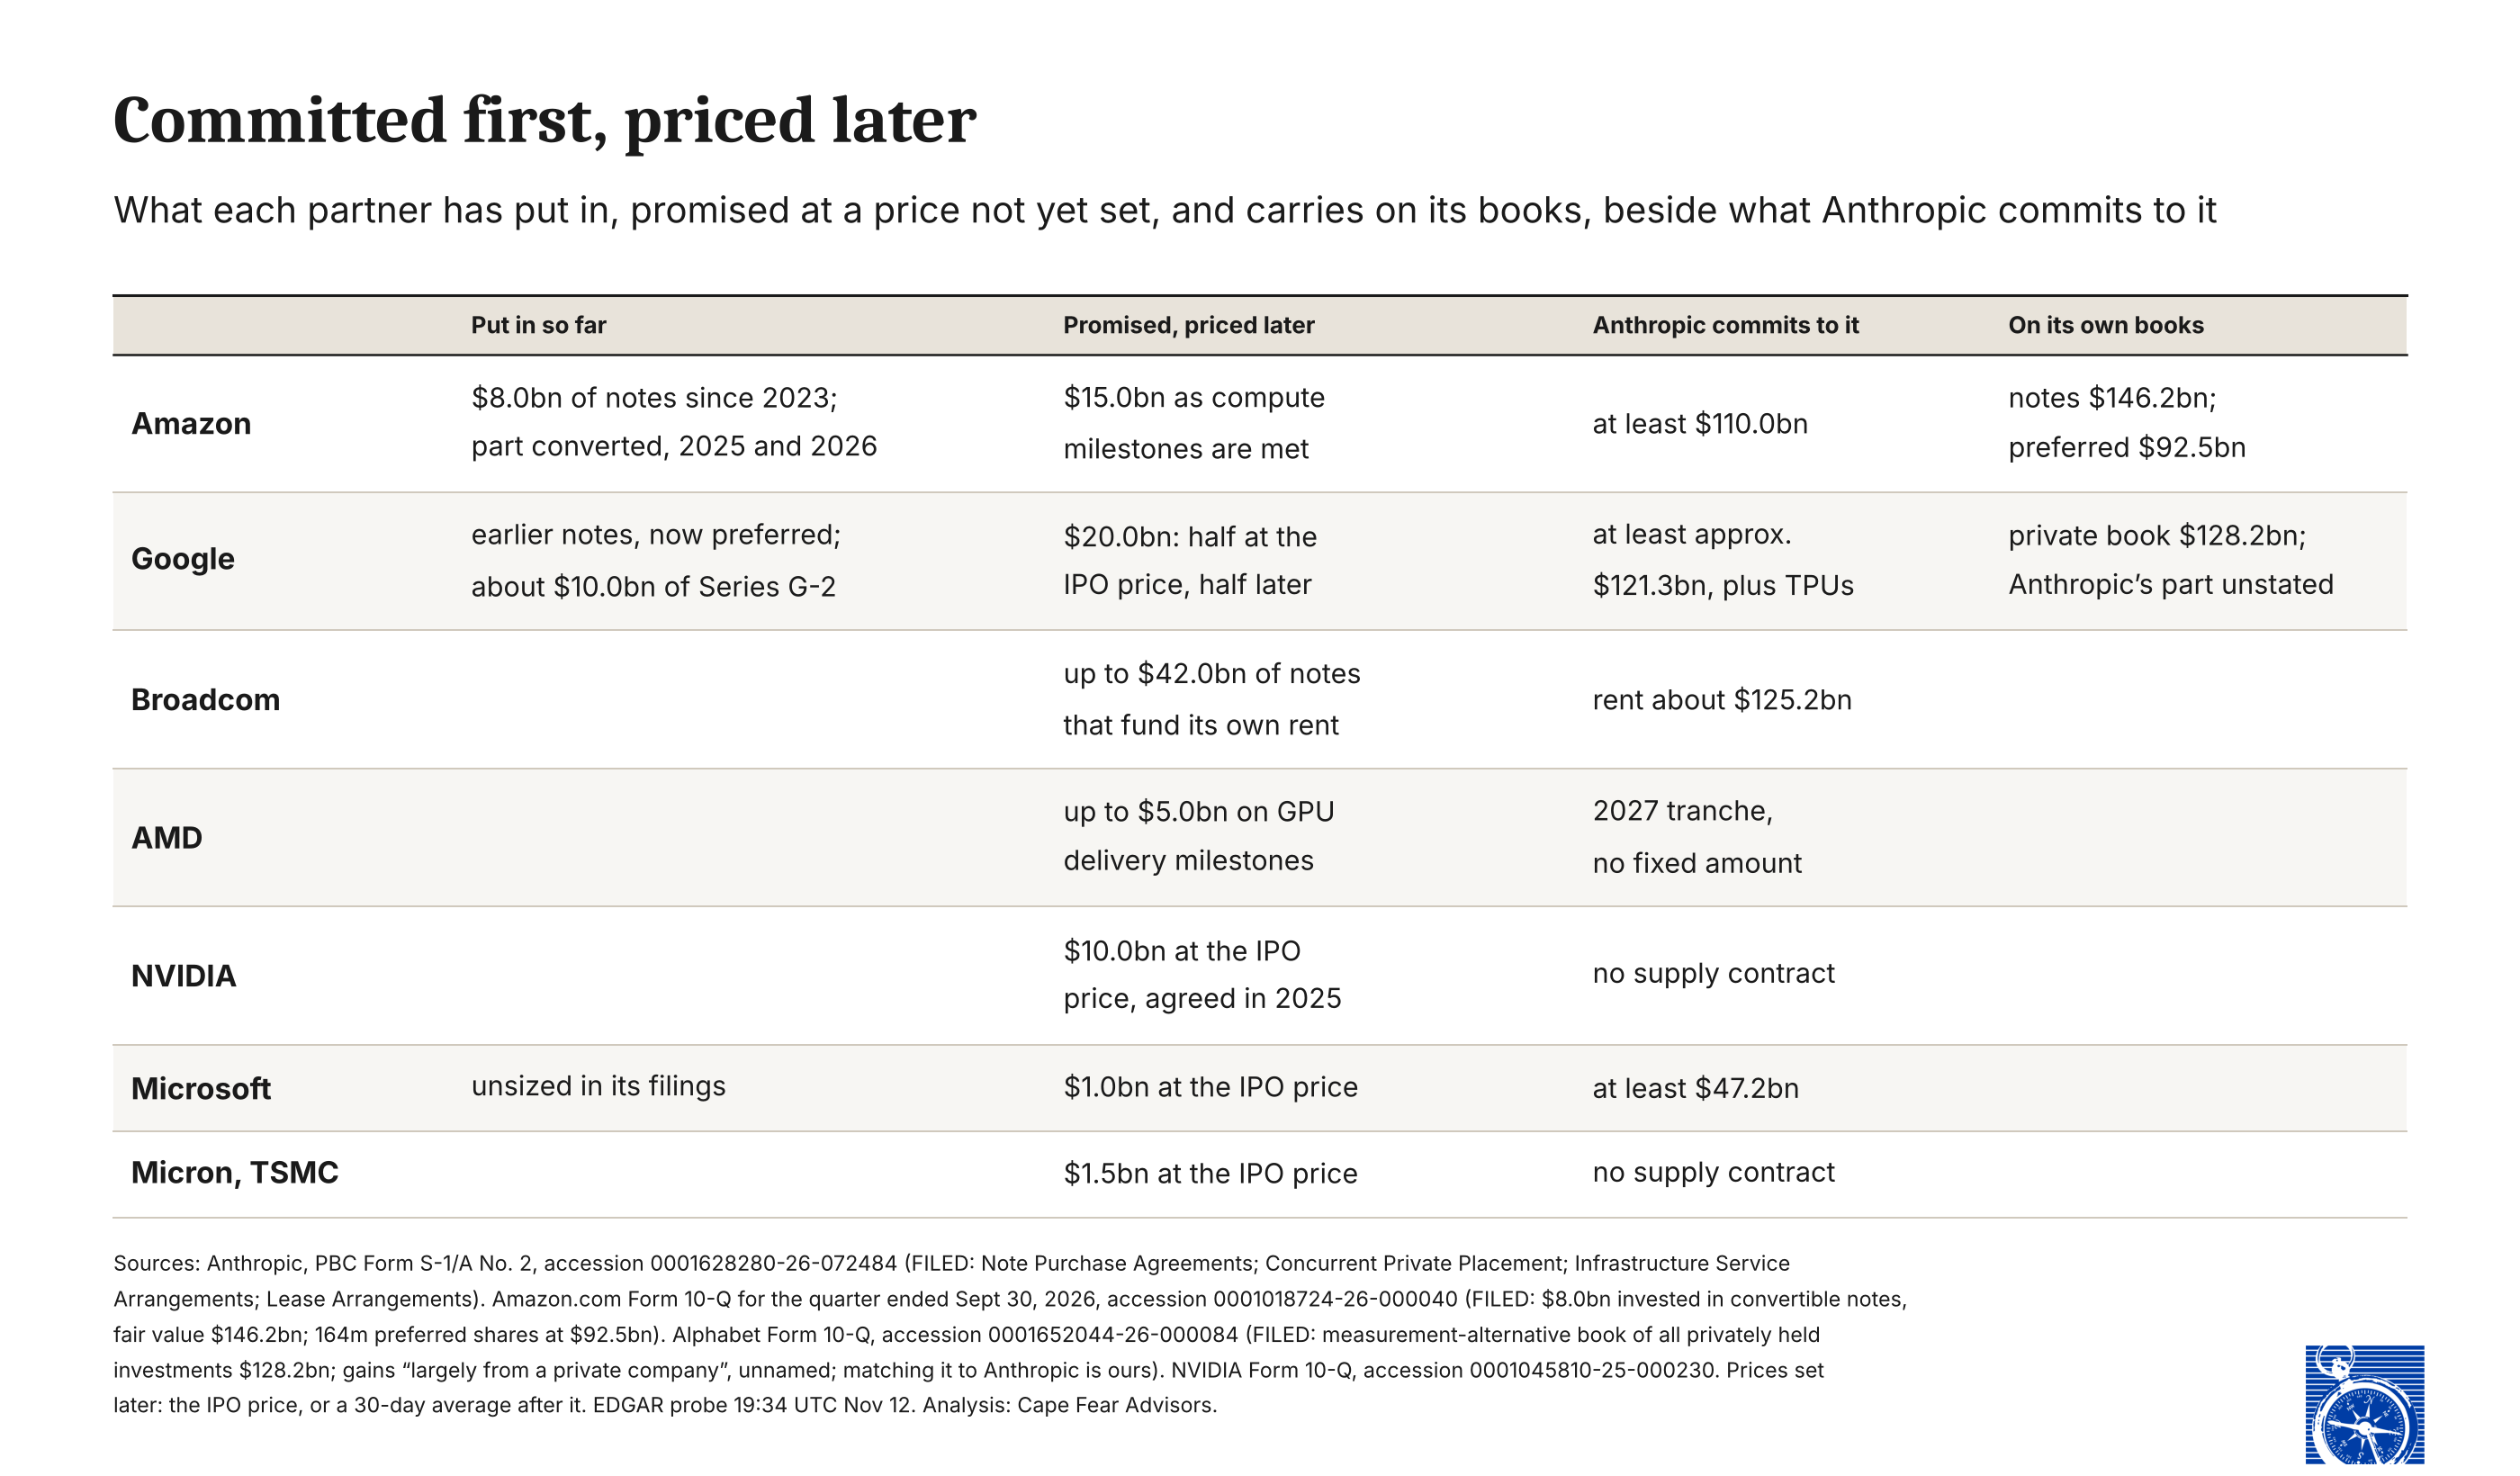
Across the placement and the later tranches, $53.5 billion of equity was committed before its price was set: $26.0 billion at the IPO price, and $27.5 billion later at trailing averages from Amazon, Google and AMD. Each later tranche is keyed to compute delivered or revenue earned. That is a middle road between a bet on the equity and a backstop for the contract. (17)
Fungible in use, contracted at the source
Anthropic describes its compute as "a single, fungible pool from multiple strategic partners." At its source the pool is contracted partner by partner: about $900.9 billion of commitments, $70.7 billion of them due in the twelve months after September 30. The fungible purchase on the record is short-term compute, $5.0 billion of it in the third quarter, "which currently costs significantly more than comparable compute procured under our multi-year commitments." Anthropic's swing from a second-quarter operating income of $974 million to a third-quarter operating loss of $567 million was "primarily driven by" that compute and $2.0 billion of non-cash donation-matching charges. (18)
The money follows the same pattern. Anthropic reported $146.6 billion of liquidity at September 30, in cash, short-term investments and its credit facility, money that can go anywhere. Its twelve-month sufficiency statement counts that cash, those investments, the facility and "cash generated from sales," and leaves the partner support out, the same line our CoreWeave reading drew between fungible cash and facilities tied to specific contracts. Beside it sits $69.5 billion of partner "funding support" once the placement closes, and each dollar of it travels one road. Broadcom's up to $42.0 billion finances rent owed to Broadcom; Amazon's $15.0 billion arrives as compute capacity milestones are met; Google's remaining $10.0 billion is keyed to third-party compute agreements and revenue targets; AMD's $2.5 billion follows its hardware agreement. About 60 percent of the contracted support returns to Broadcom as rent. (19)
The contracts also bind with different force. Google's, Amazon's, Microsoft's and Broadcom's are non-cancelable except for breach or default. Either party may cancel each SpaceXAI agreement on 90 days' notice after initial periods ending in early 2027; Nscale must use "best efforts to obtain qualifying financing"; and of Lambda's $41.3 billion, about $34.9 billion "is currently terminable by either party," with no notice delivered. (20)
The web is visible from its small end. A tie shows in the filings of the company for which it is large, in the documents an event forces, and in Anthropic's prospectus; it seldom shows by name in a large counterparty's own reports. A Microsoft shareholder learns of the tie from Anthropic's prospectus, an Alphabet shareholder learns whose tie it is, and Akamai's shareholders learned of theirs from Akamai. After the IPO, Anthropic's quarterly reports become the one recurring document that names all of them, from one side, and the census can be run again each quarter against the counterparties' filings.
What the next documents settle
Anthropic's pricing amendment, expected November 18: the price, and so the shares each placement buyer receives; the seven names and $26.0 billion; Lambda's August agreement.
NVIDIA's 10-Q, expected November 17: whether the $25 billion of equity investment commitments changes, and whether Anthropic is named again. (21)
Alphabet's, Microsoft's and AMD's next reports: whether "a private company" acquires a name.
Free to read, no paywall. Readers who find the work useful can support it at the foot of the page; payment offsets the time and buys no access. Corrections run in daylight, dated, in a comment or in the following piece, and a reader who finds one is doing us a favor.
Standing Disclosure
Cape Fear Advisors holds no direct position, long or short, in the securities discussed here. Any exposure is indirect, through managed funds it does not control, which may include index funds holding the public companies named.
Anthropic is the developer of Claude, which is used in preparing this research, and Anthropic is the company at the center of this piece: it is the counterparty to every tie read here, and the companies whose stakes and commitments the piece measures are its investors and suppliers. That nearness cannot be fully checked away, which is why no claim here rests on trust in the tool: every figure carries a public source, and the record grades the rest. Others named in this piece have ties to Anthropic: Amazon, Google and Microsoft are investors and cloud suppliers; NVIDIA, AMD, Broadcom, Micron and TSMC are buyers in its private placement, and NVIDIA, AMD, Broadcom and Micron supply the chips behind its compute; SpaceX, Nscale, Lambda, Akamai, TeraWulf, Hut 8 and CoreWeave supply or host its capacity; Apollo finances capacity built for it. Companies not named here may hold positions or supply relationships that bear on the filers discussed, and that possibility is part of why every piece is re-checked for bias, ground facts, and filings rather than read against a fixed list. Figures are quoted from the filers without characterization, and the same standard of reading is applied to every filer named.
Notes
[1] FILED: name counts, Anthropic, PBC Form S-1/A No. 2, accession 0001628280-26-072484, and each counterparty's filings dated Jan 1 to Nov 13, 2026, "Anthropic" counted as a word; furnished releases not counted. First run 20:05 to 20:15 UTC Nov 12; re-run on every counterparty filing dated Nov 12 and 13 at 14:03 UTC Nov 13, rows unchanged (the one new naming is Nscale's S-1/A 0001193125-26-458722, 46 instances, already a both-sides row). Anthropic's own filings since S-1/A No. 2 are free writing prospectuses only. Eighteen ties: Amazon, Broadcom, Nscale, SpaceX (both); Google equity, Google cloud, Microsoft, AMD, NVIDIA, Micron, TSMC, Lambda (Anthropic only); Akamai, Apollo, TeraWulf, Hut 8 (counterparty only); CoreWeave, the lessor's warrant (neither). Amazon 10-Q 0001018724-26-000040; Broadcom 8-K 0001193125-26-144028; Nscale S-1 0001193125-26-395475; SpaceX prospectus 0001628280-26-042639; Alphabet 10-Q 0001652044-26-000084; Microsoft 10-Q 0001193125-26-436133; AMD 10-Q 0000002488-26-000191; NVIDIA 10-Q 0001045810-25-000230; Akamai 8-K 0001193125-26-401048; CoreWeave 10-Q 0001769628-26-000465.
[2] FILED: Broadcom 10-Q 0001730168-26-000080 ("our customer"); SpaceX 10-Q 0001628280-26-066880 ("Customer B," 34.5% of Q3 revenue). Among the counterparty-only rows, Akamai's and Apollo's 10-Qs name Anthropic; the sentence covers the four named on both sides.
[3] OURS on FILED. Yearly value is the commitment divided by its stated term, or the filed monthly rate:
[4] OURS on FILED: Amazon's marks $238.7bn / $716.9bn = 33.3%. FILED: Alphabet 10-Q 0001652044-26-000084: "the carrying value of our non-marketable equity securities accounted for under the measurement alternative was $128.2 billion" at Sep 30, 2026, the whole book of privately held investments; nine-month gains "largely from a private company." OURS: $128.2bn / $402.8bn = 31.8%, floored; Alphabet's Anthropic share of the book is unstated, so 31 percent is a ceiling for that position, and the body claims no comparison of size beyond it.
[5] FILED: S-1/A No. 2, Principal and Selling Stockholders; Certain Relationships and Related Party Transactions; Note Purchase Agreements (ownership caps).
[6] FILED: Amazon.com Form 10-Q, accession 0001018724-26-000040: "From Q3 2023 to Q4 2025, we invested $8.0 billion in convertible notes"; "In Q1 2025 and Q1 2026, a portion of the then-outstanding notes was converted to nonvoting preferred stock"; notes at fair value $146.2bn; 164 million preferred at $92.5bn. OURS: $146.2bn + $92.5bn = $238.7bn; $238.7bn / $110.0bn = 2.17.
[7] FILED: Amazon 10-Q per note 6: the notes are "classified as available-for-sale and reported at fair value," using inputs including "estimates of expected time to and type of liquidity events and anticipated securities offerings"; the preferred is "initially recorded at their estimated fair value at the time of each conversion... with future adjustments for observable changes in prices or impairments"; upward adjustments of $39m in Q3 2026; "Each share of nonvoting preferred stock held by us is convertible into ten shares of nonvoting common stock"; the notes "would convert to approximately 184 million shares of nonvoting preferred stock" without the cap. FILED: S-1/A No. 2: Series H-1 sold May to June 2026 "at a purchase price of $589.0095 per share"; 10-for-1 split effected Sep 17, 2026, with preferred conversion rates "proportionately adjusted." OURS: $146.2bn / 1,840.4m = $79.44; $92.5bn / 1,640m = $56.40; $79.44 / $56.40 = 1.408, floored to 40 percent; $589.0095 / 10 = $58.90. The 4 percent between $56.40 and $58.90 is unexplained in Amazon's filing.
[8] FILED: S-1/A No. 2: notes outstanding "consist entirely of non-interest-bearing rollover notes issued to Amazon," principal $6,203m at fixed conversion prices of $2.0928 and $5.0478, 1,840,444,962 Class N issuable before the 12% cap; convertible notes at fair value $130,502m at Sep 30, 2026, Level 3, under the fair value option. OURS: $130,502m / 1,840.4m = $70.91; $146.2bn minus $130.5bn = $15.7bn; $79.44 / $70.91 = 1.12. The per-share figures use the pre-cap count at the fixed prices. Notes above the cap roll over and convert later at the lowest of the fixed price, the IPO price and a 10-day VWAP; a conversion price below the fixed price would raise the count and lower both per-share marks. The $15.7bn gap is in dollars and is unaffected. The range is dated Nov 10. Fair value of a liability includes nonperformance risk (ASC 820); the "expected" gap is OURS. FILED: S-1/A No. 2, change in fair value of convertible notes payable $94,324m for the nine months to Sep 30, 2026 (Level 3 rollforward); the expense was "primarily driven by increases in the fair value of our outstanding convertible promissory notes resulting from increases in our enterprise valuation."
[9] FILED: Akamai Technologies Form 8-K, accession 0001193125-26-401048: 387,051 shares of Series B Non-Voting Convertible Preferred, 7,741,020 common as converted, $111.33 per common share; vesting 40 percent "upon the first payment by Anthropic... under Project Plan 3" and 20 percent "upon each additional $3.0 billion of contractual value committed"; exercisable to the seventh anniversary. OURS: $11.6bn + 3 × $3.0bn = $20.6bn; 5.386 percent of shares outstanding, floored to 5.3, on the share count in Akamai's 10-Q 0001086222-26-000086.
[10] FILED: Akamai Form 8-K, accession 0001193125-26-455539, Ex. 99.1: $1.1bn of 1.00% Convertible Senior Notes due Nov 15, 2028, convertible at about $112.41 (a 40.0% premium to the $80.29 close on Nov 9), and $1.1bn of 1.00% Convertible Senior Notes due Nov 15, 2031, at about $102.37; use of proceeds as quoted. OURS: $112.41 minus $111.33 = $1.08; $111.33 / $80.29 = 1.387, floored to 38 percent. FILED: Akamai Form 8-K, accession 0001193125-26-458699, Nov 12, 2026, Items 1.01, 2.03 and 3.02: each tranche closed at an aggregate principal amount of $1,250,000,000, both at 1.00%, under indentures dated Nov 12, 2026; the increase from $1.1bn each is the initial purchasers' options. The closing 8-K names Anthropic zero times.
[11] FILED: S-1/A No. 2, Fair Value Measurements, Level 3 (warrant rights $345m at Dec 31, 2025, $1,128m at Sep 30, 2026; nine-month change in fair value $783m).
[12] FILED: S-1/A No. 2, Infrastructure Service Arrangements and Lease Arrangements. Quoted bases: Google "at least approximately $121.3 billion... regardless of actual usage"; Microsoft "at least $47.2 billion and up to $49.2 billion"; Amazon "at least $110.0 billion"; TPU compute estimated at "approximately $125.0 billion to $150.0 billion," outside the contractual obligations table; Broadcom, rent. The original S-1's $114.5bn (Google) and $44.9bn (Microsoft) are superseded.
[13] FILED: S-1/A No. 2 (SpaceXAI up to $120.5bn; Nscale up to about $44.6bn; Lambda about $41.3bn). OURS: the sum. FILED: NSCALE Ltd Form S-1, accession 0001193125-26-395475, NVIDIA Warrants and Guarantee (Guarantee of Lease Agreement of October 14, 2025, Ward County, Texas, "up to a maximum amount of $860.3 million" for the first five years, in consideration for Non-Default and Default warrants). Whether the Ward County facility serves the Anthropic agreements is not stated. Micron and TSMC appear in Anthropic's risk factors as a memory maker and as the foundry behind its Taiwan concentration; their own filings name Anthropic zero times. The required share: "The Required Share," Aug 23, 2026; "NVIDIA, What Comes Back," Aug 22, 2026.
[14] FILED: S-1/A No. 2: Concentrations of Risk (CSP marketplace sales about 11%, 32%, 47% and 44% of revenue in 2023, 2024, 2025 and the nine months to Sep 30, 2026; 42%, 60% and 52% of net receivables at Dec 31, 2024, Dec 31, 2025 and Sep 30, 2026); revenue recognition ("the Company is the principal and recognizes revenue on a gross basis"); expense captions ("channel partner costs" in sales and marketing; "payment processing and platform fees" in other operating and administrative expenses). The amounts by CSP are not given.
[15] FILED: S-1/A No. 2, Note Purchase Agreements; Lease Arrangements (restricted cash deposit "for the benefit of Broadcom"); Infrastructure Service Arrangements; Amazon 2026 NPA.
[16] FILED: S-1/A No. 2, Concurrent Private Placement; Google 2026 NPA ("funding a portion of its previously committed investment obligations"); AMD letter agreement ("will satisfy a portion"). FILED: NVIDIA Form 10-Q, accession 0001045810-25-000230 ("agreement, subject to certain closing conditions, to invest up to $10 billion in Anthropic"). OURS: the link; $22.5bn / $26.0bn = 86.5%, floored; 801,351,354 primary shares at $74 is $59.3bn ($56.1bn to $62.5bn across the range); $59.3bn / ($59.3bn + $3.5bn of new placement) = 94.4%, floored. The 23,648,646 secondary shares pay the seven co-founders, 3,378,378 each; no investor-supplier sells.
[17] OURS on FILED: $26.0bn + $15.0bn (Amazon) + $10.0bn (Google, second half) + $2.5bn (AMD) = $53.5bn. FILED: Alphabet 10-Q per note 4 ("$20.0 billion of future capital funding commitments with a private company"). OURS: the match to Anthropic.
[18] FILED: S-1/A No. 2, Business, Our Approach to Compute ("We manage compute as a single, fungible pool from multiple strategic partners, and we dynamically direct available compute between workloads based on where the marginal unit is expected to be most productive at any given time"); aggregate committed spend about $900.9bn; "Approximately $70.7 billion of these commitments are due in the 12 months following September 30, 2026," of which about $4.2bn relates to arrangements subject to contingent conditions or termination rights. These supersede the $895.4bn, $69.8bn and $4.3bn in S-1/A No. 1 (Nov 2), which our pieces of Oct 31 and Nov 2 printed. Anthropic's November 2026 investor fact sheet repeats the pool language and the $900B and $70.7bn figures. FILED: Key Factors and Non-GAAP Financial Measures (the $5.0bn quote; "primarily driven by" the $5.0bn "and $2.0 billion of non-cash charges related to our donation matching program"); operating income $974m (Q2 2026), operating loss $567m (Q3 2026).
[19] FILED: S-1/A No. 2, Liquidity and Capital Resources: "$146.6 billion of liquidity, consisting of $95.6 billion of cash and cash equivalents, $36.3 billion of short-term investments, and $14.8 billion of availability under our A&R Credit Facility"; "significant funding support from our strategic partners, including up to $77.0 billion in available financing capacity under our NPAs and up to $5.0 billion in equity commitments (of which $10.0 billion and $2.5 billion, respectively, will be reduced upon the closing of the concurrent private placement)." The components are rounded as filed: the three printed figures sum to $146.7bn; the balance sheet gives $95,562m and $36,283m, which with the facility round to the stated $146.6bn. Note Purchase Agreements (Broadcom up to $42.0bn "to finance obligations under the 2026 Lease Arrangement"; Amazon "in $5.0 billion increments following the achievement of the relevant compute capacity milestones"; Google draws "driven by the achievement of certain conditions under certain third-party compute agreements and specified TTM revenue targets"); AMD letter agreement ("if certain conditions are achieved"). Sufficiency statement: "We believe our existing available cash and cash equivalents and short-term investments, together with cash generated from sales and amounts available under our A&R Credit Facility, will be sufficient to support working capital, operating and finance lease payments, and capital expenditure requirements for at least the next 12 months from the date of this prospectus." Restricted cash of $2,540m, plus $50m in current assets, sits outside the $146.6bn, and the company "may be required to restrict up to an additional $10.0 billion for future amounts due, under certain arrangements," none in effect at Sep 30. CoreWeave: "CoreWeave, the Key, the Lock and the Clock," Aug 20, 2026. OURS: $77.0bn + $5.0bn minus $12.5bn = $69.5bn; $77.0bn = $20.0bn (Google) + $15.0bn (Amazon) + $42.0bn (Broadcom); $42.0bn / $69.5bn = 60.4%, floored.
[20] FILED: S-1/A No. 2, Infrastructure Service Arrangements: SpaceXAI, each agreement "may be cancelled by either party upon 90 days' advance written notice" after initial periods ending in January and March 2027; Lambda's August agreement "is currently terminable by either party" because "Lambda did not secure the facility lease by such date"; no notice of termination has been delivered, and Anthropic has no current intention to terminate.
[21] FILED: NVIDIA Form 10-Q, accession 0001045810-26-000075 ($25bn of equity investment commitments at Jul 26). FILED: NVIDIA Form 8-K, accession 0001045810-26-000082, Ex. 99.1: results "on Tuesday, November 17, at approximately 1:20 p.m. PT, as previously scheduled." The Nov 18 date is REPORTED.
Analysis: Cape Fear Advisors.
This piece also appears on Substack. Cape Fear Advisors is an independent advisory firm based in Portsmouth, NH.
Contact Cape Fear Advisors